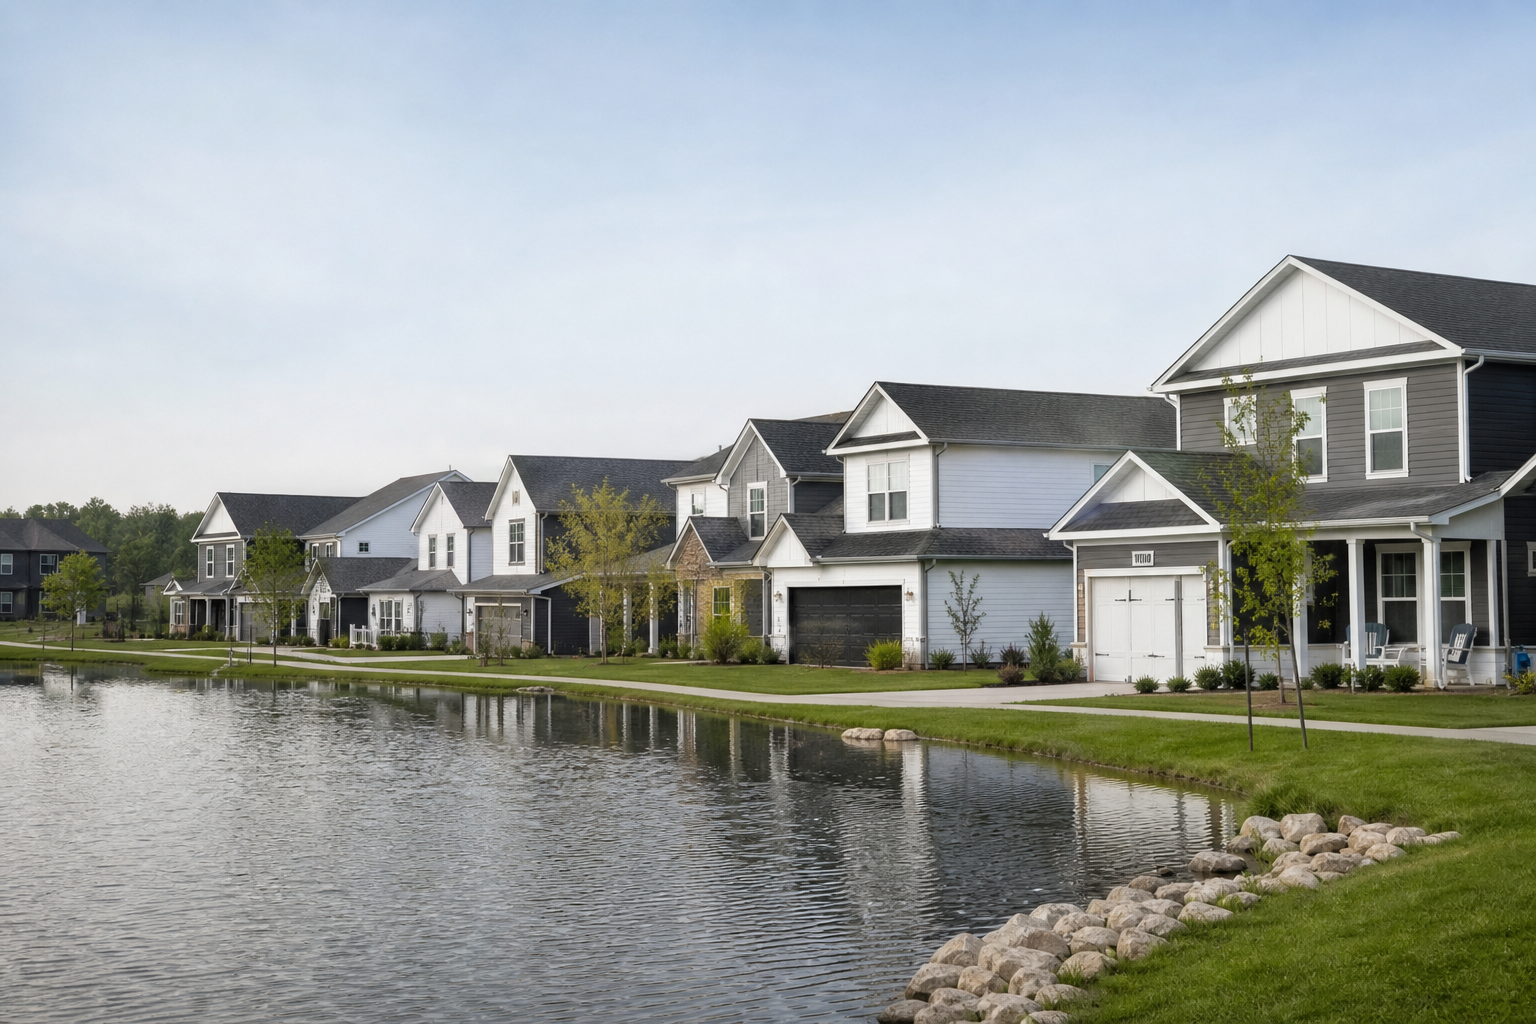
Marcus & Millichap Capital Corporation arranged a $53M, three-year, nonrecourse refinancing of The Grove, a 235-unit build-to-rent community in Rogers, Arkansas, for a joint venture of Brittenum Group and Realty Capital Partners. The 2024-delivered community comprises 123 detached two-story cottages and 112 attached townhomes and is 94.5% occupied, with a median resident household income of about $100,000. The stated purpose: repay the construction loan ahead of maturity and season the rent roll ahead of a sale. John Brickson of MMCC Dallas arranged the loan.
The Signal. $225,532 of debt per unit. A three-year term on a 2024 delivery is a 2029 exit clock, set deliberately. Rate, lender, LTV and the retired construction balance are undisclosed, so no spread math is possible.
The construction loan was not in trouble; it was prepaid so the asset could carry three years of stabilized operating history into a sale process instead of one. Northwest Arkansas is the point: a $100,000 median resident income on cottage product in a market anchored by Walmart, Tyson and J.B. Hunt is the BTR thesis in its purest form — renters who could buy, choosing not to. Whether that holds into a 2029 for-sale market is the bet behind $53M of nonrecourse debt.
Implications. BTR sponsors are trading construction debt for term debt not because they must but to manufacture the operating history institutional buyers demand. Expect more prepay-and-season refinancings on 2023–2024 deliveries.
Uncertainty: single press-release origin; rate, lender and LTV undisclosed.
Related coverage
Key Takeaways
- The refi was not a rescue — it was a three-year runway to sell.
- BTR sponsors are buying operating history with term debt.
- Northwest Arkansas cottage product at $100K household incomes is the BTR thesis in its purest form.
BusinessWire (Marcus & Millichap Capital Corporation), Sept 14, 2026 — MMCC arranges $53 million build-to-rent refinancing · Yield PRO, Sept 14, 2026 — The Grove, Rogers AR (same release)
Never miss a Signal
Get the daily brief that busy CRE professionals rely on.