TruAmerica Pays $78M, About $390K A Unit, For Bay Area Apartments
Seller Acacia paid $40M in 2011; the buyer will renovate 192 of 200 units on turnover.
CRE360 Editorial Desk·Oct 11, 2026
Apartments, BTR & residential rentals
Seller Acacia paid $40M in 2011; the buyer will renovate 192 of 200 units on turnover.
Madison Realty Capital refinances a newly built 502-unit Fort Lauderdale community with $10M of public support.
Apartment values are down, CMBS stress is climbing, and $757B of debt matures by 2028.
Millburn & Co. paid $58.7M -- $225,769 a unit -- for Ascend at Black Canyon.
Decron paid $114M in L.A.'s Miracle Mile; TA Realty paid $102M outside Seattle. Both cite replacement cost.
Two ground-up loans in 48 hours — Chicago's West Loop and suburban Boston — while August five-plus starts fell 22.5%.
Both ordinances passed committee 24 hours apart. One charges landlords $20 to $60 a unit; the other exempts owners of up to 12.
August starts missed at 1.275M; five-plus-unit starts dropped to 344,000 while a D.C. conversion still found $92M.
Northwest Arkansas cottages and townhomes are currently at 94.5% occupancy and are being financed for a 2029 exit.
Time Equities is launching a $95.3 million tenant-in-common raise for a 465-unit project in Boynton Beach.
A short-term-rental platform is now a below-market last-dollar lender to stalled apartment projects.
PGIM incurs a loss of 17.5% on its 2021 Anaheim product, while Nuveen records a gain of 20.6% on its 2019 Sammamish product.
The country’s second-largest senior housing market has just reported a scarcity number.
Chicago's first city-backed Loop conversion opened this week, and the subsidy math is the comp everyone should be reading.
Sequel and Evergreen Gavekal pay $368,947 a door in a market where the debt still clears.
A 42-year-old Atlanta-suburb complex resold for $110 million eight years after trading at $72.5 million.
A 1997-vintage suburban property outperformed its 2015 basis by 31%, exceeding the growth over an impressive eleven years.
The middle market's largest consolidation in five years priced units within 3% of a private trade the same day.
CIM and Tokyo-listed Hulic took out a White Plains lease-up barely a year old.
A 2022 delivery exited into its own loan maturity for $110M.
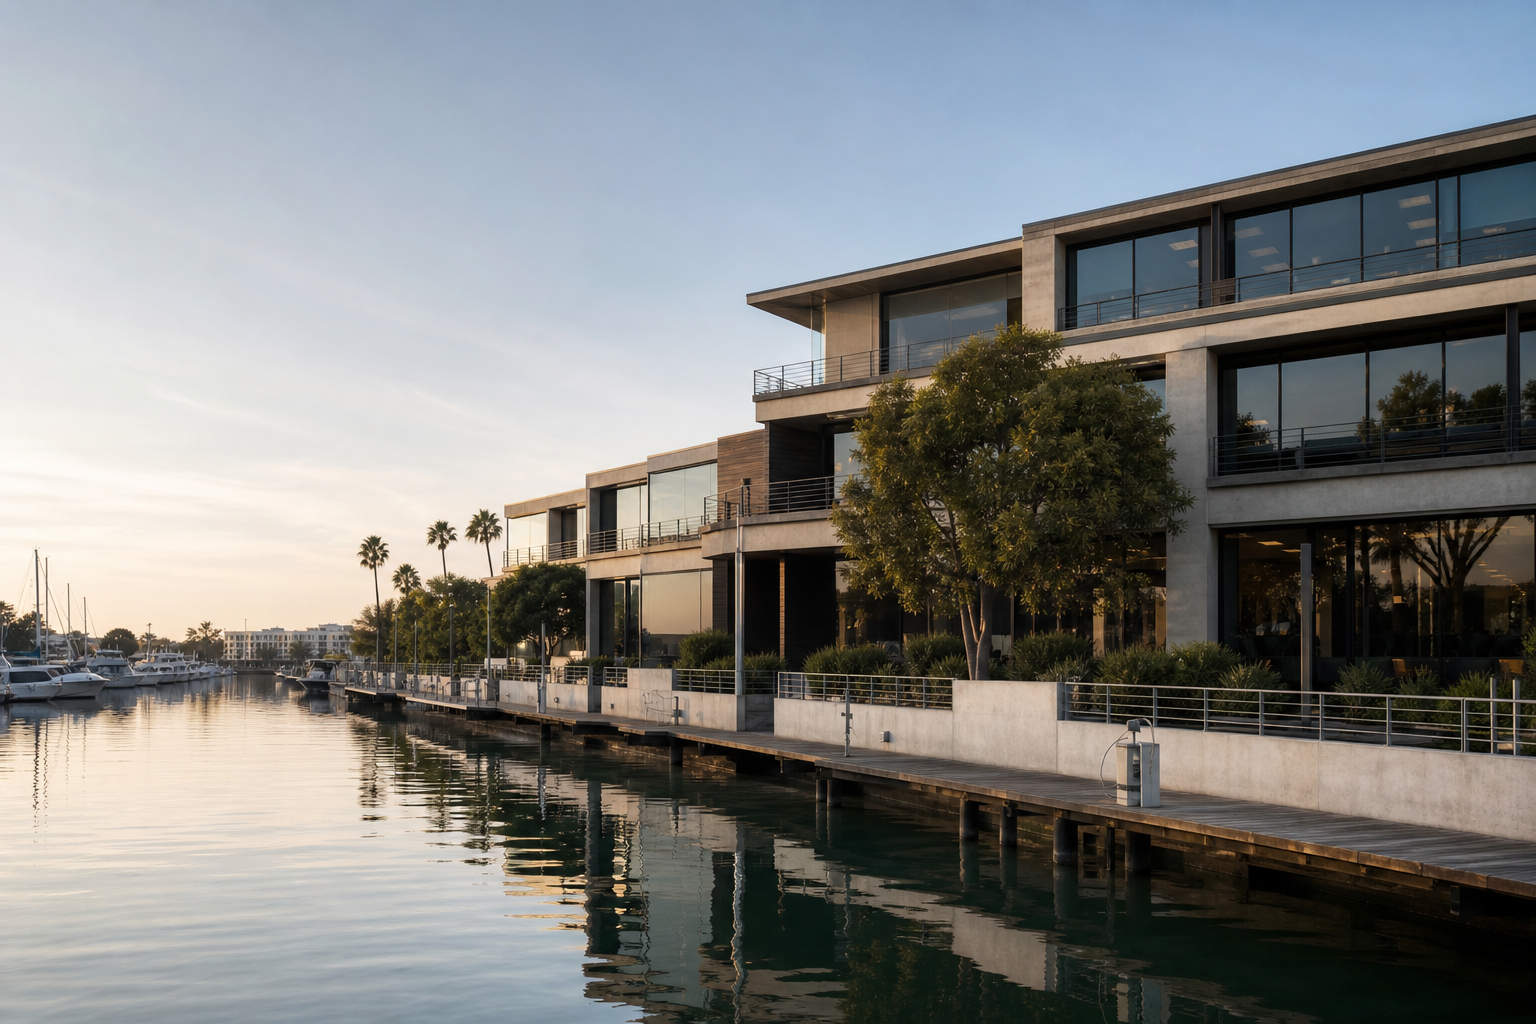
A Marina del Rey leasehold cleared at $24.8M — against $64.6M of basis.
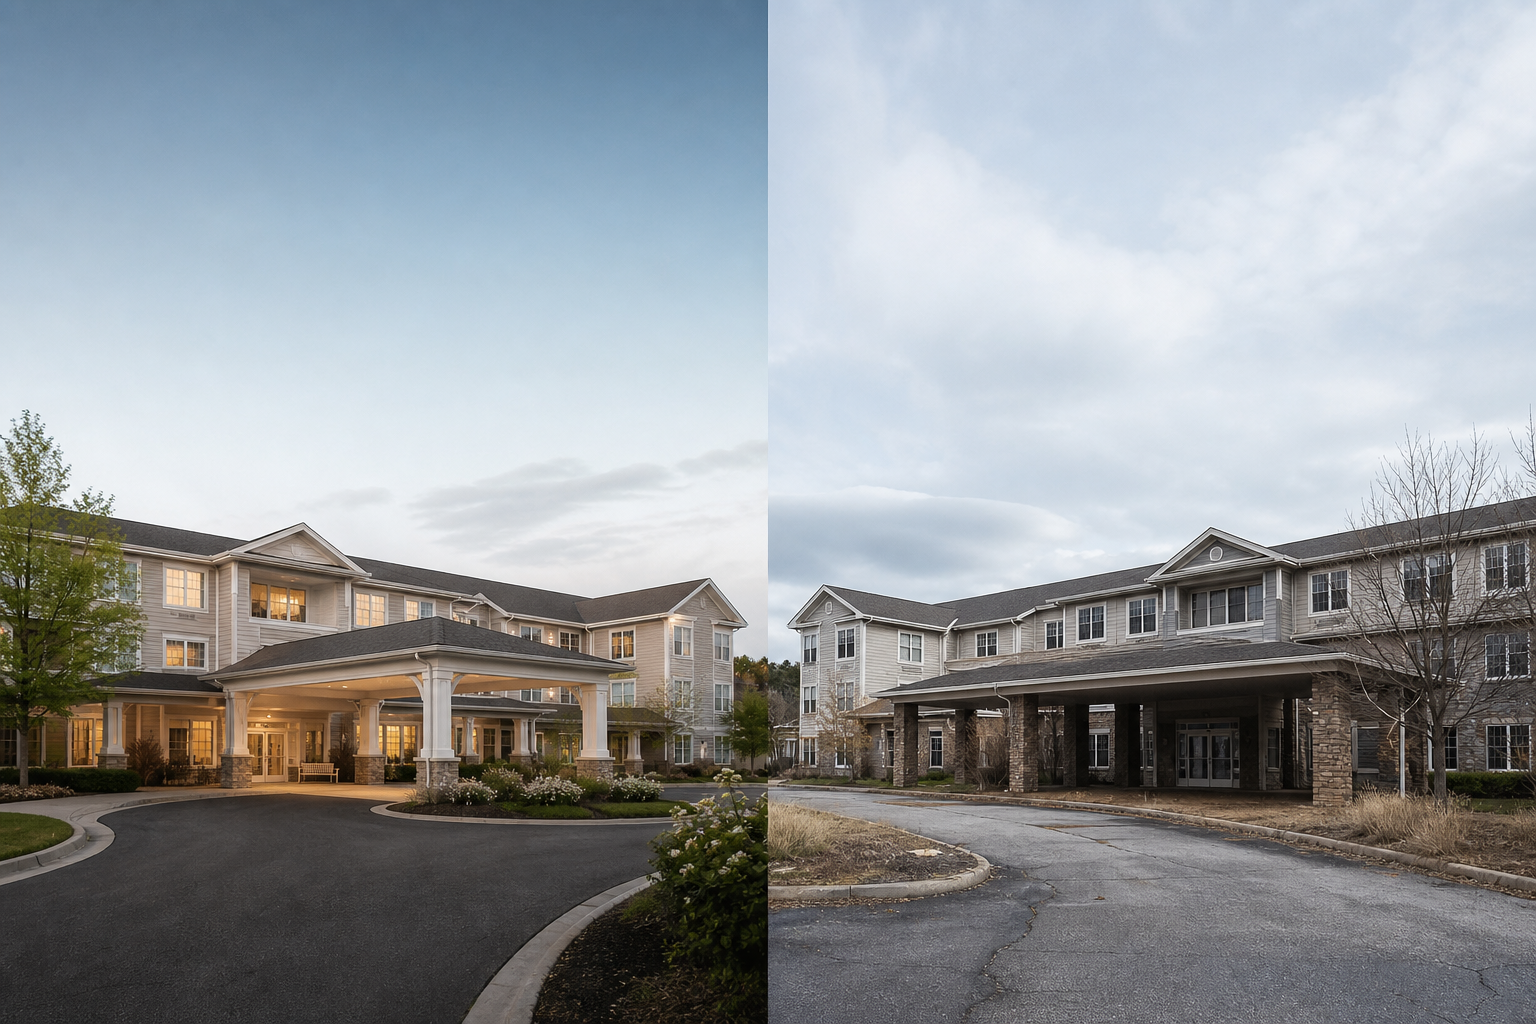
American Healthcare REIT spent $1.268 billion on senior housing in twenty-one days — at a 53.6% per-unit spread.
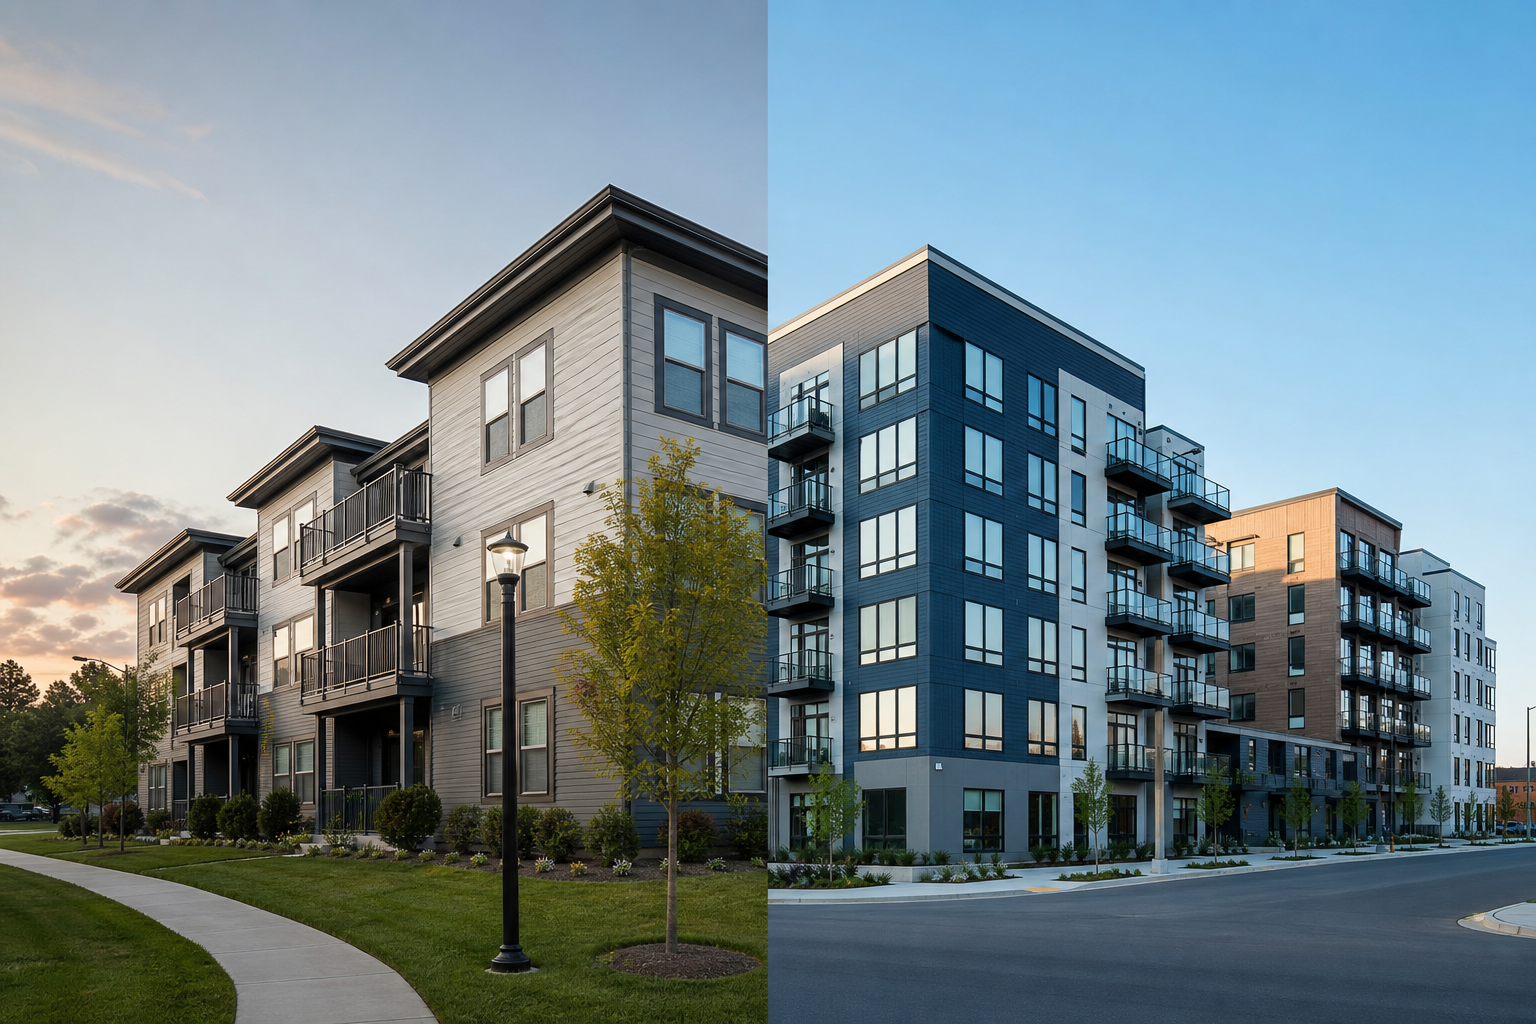
$142 million of 221(d)(4) debt across 612 Virginia units priced almost identically per door.
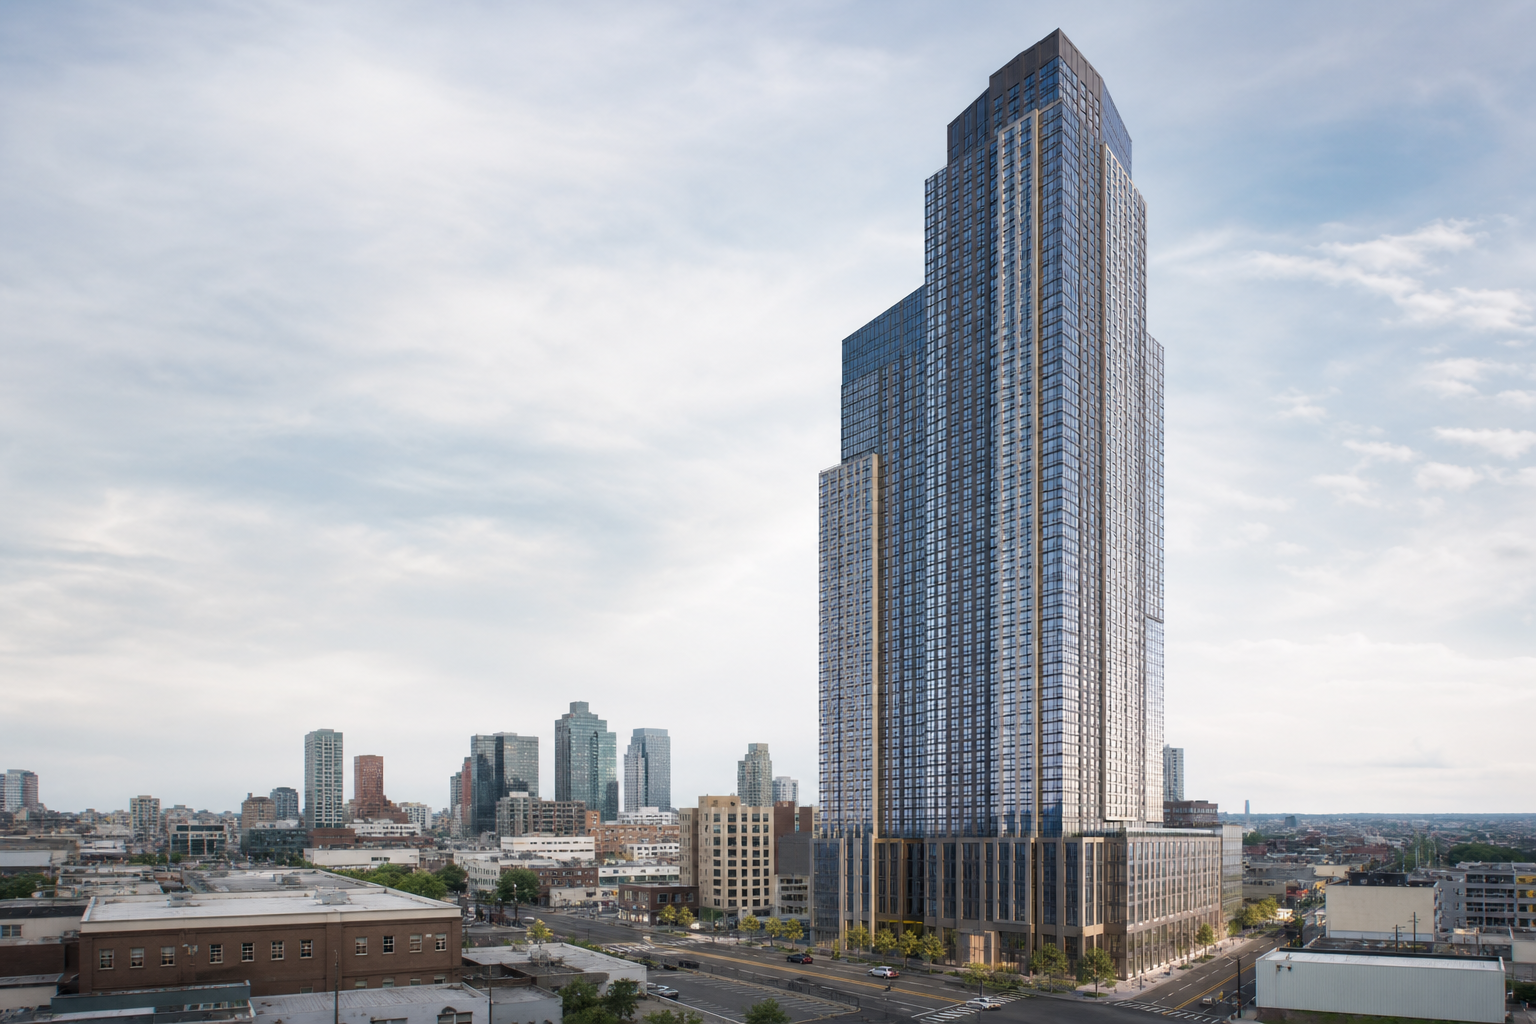
Affinius funds 1,049 units and 47 stories in Journal Square.
$778 million posted for September auction. $562 million of it is multifamily.
Knightvest takes 1,027 North Austin units off a seller who bought at the top.
A four-property 2,316-bed portfolio traded. Three of the four were built by the seller.
Kennedy Wilson's first Georgia development is funded by a contractor, not a fund.
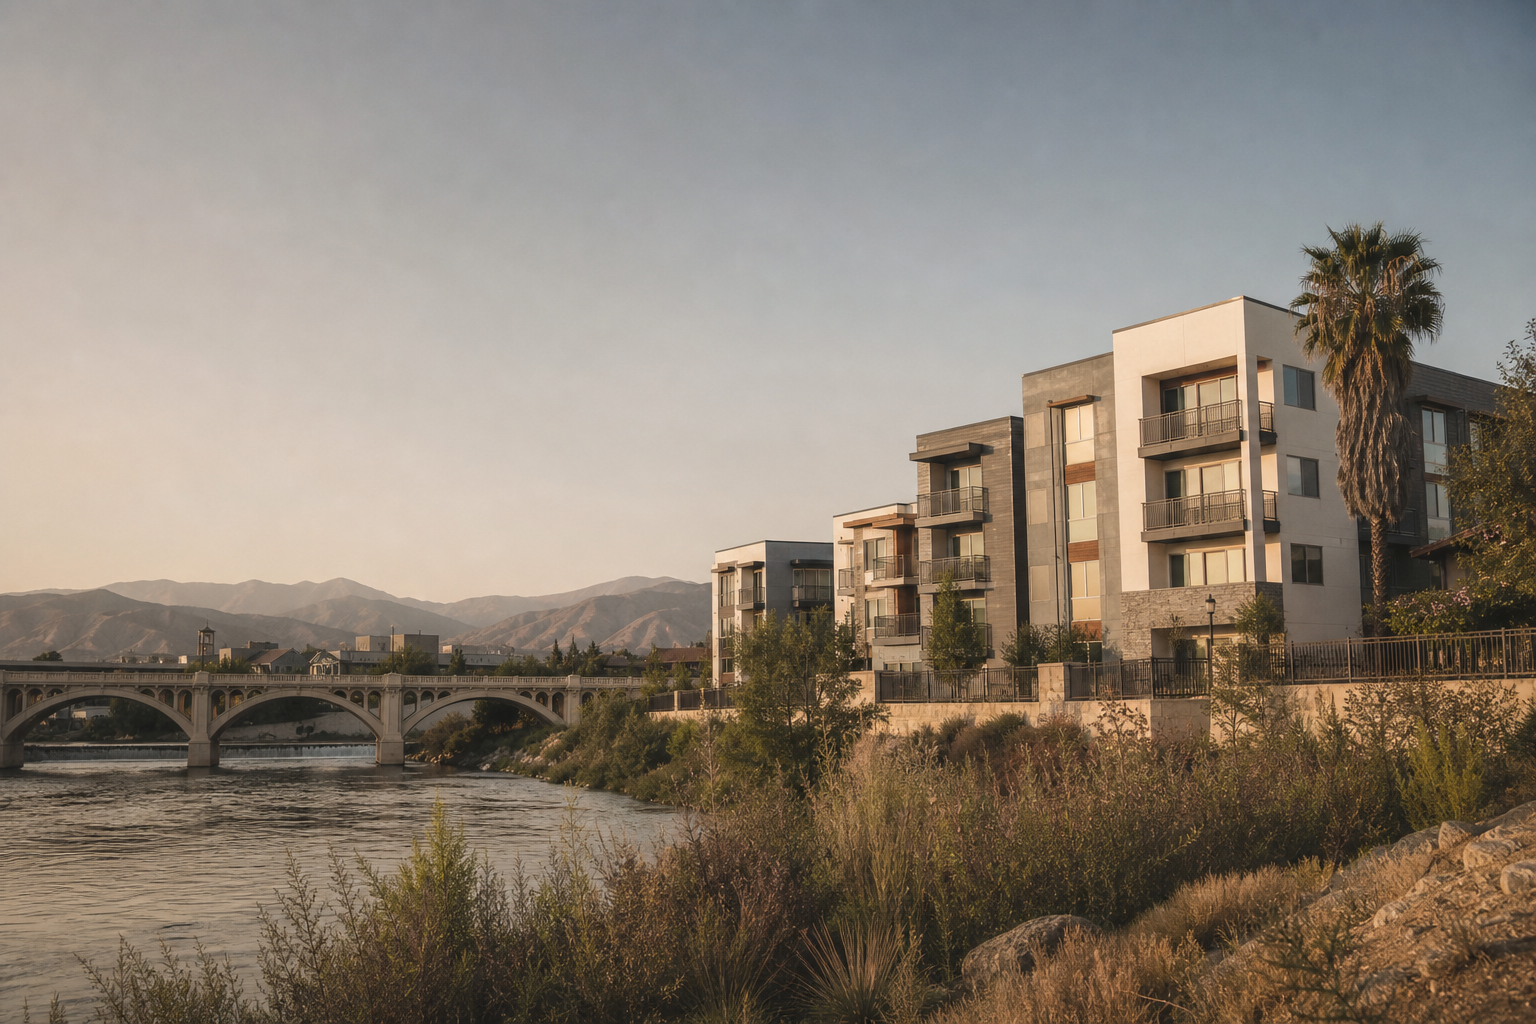
Canyon and J.P. Morgan wrote $415,000 a door in August. In March it was $393,000.
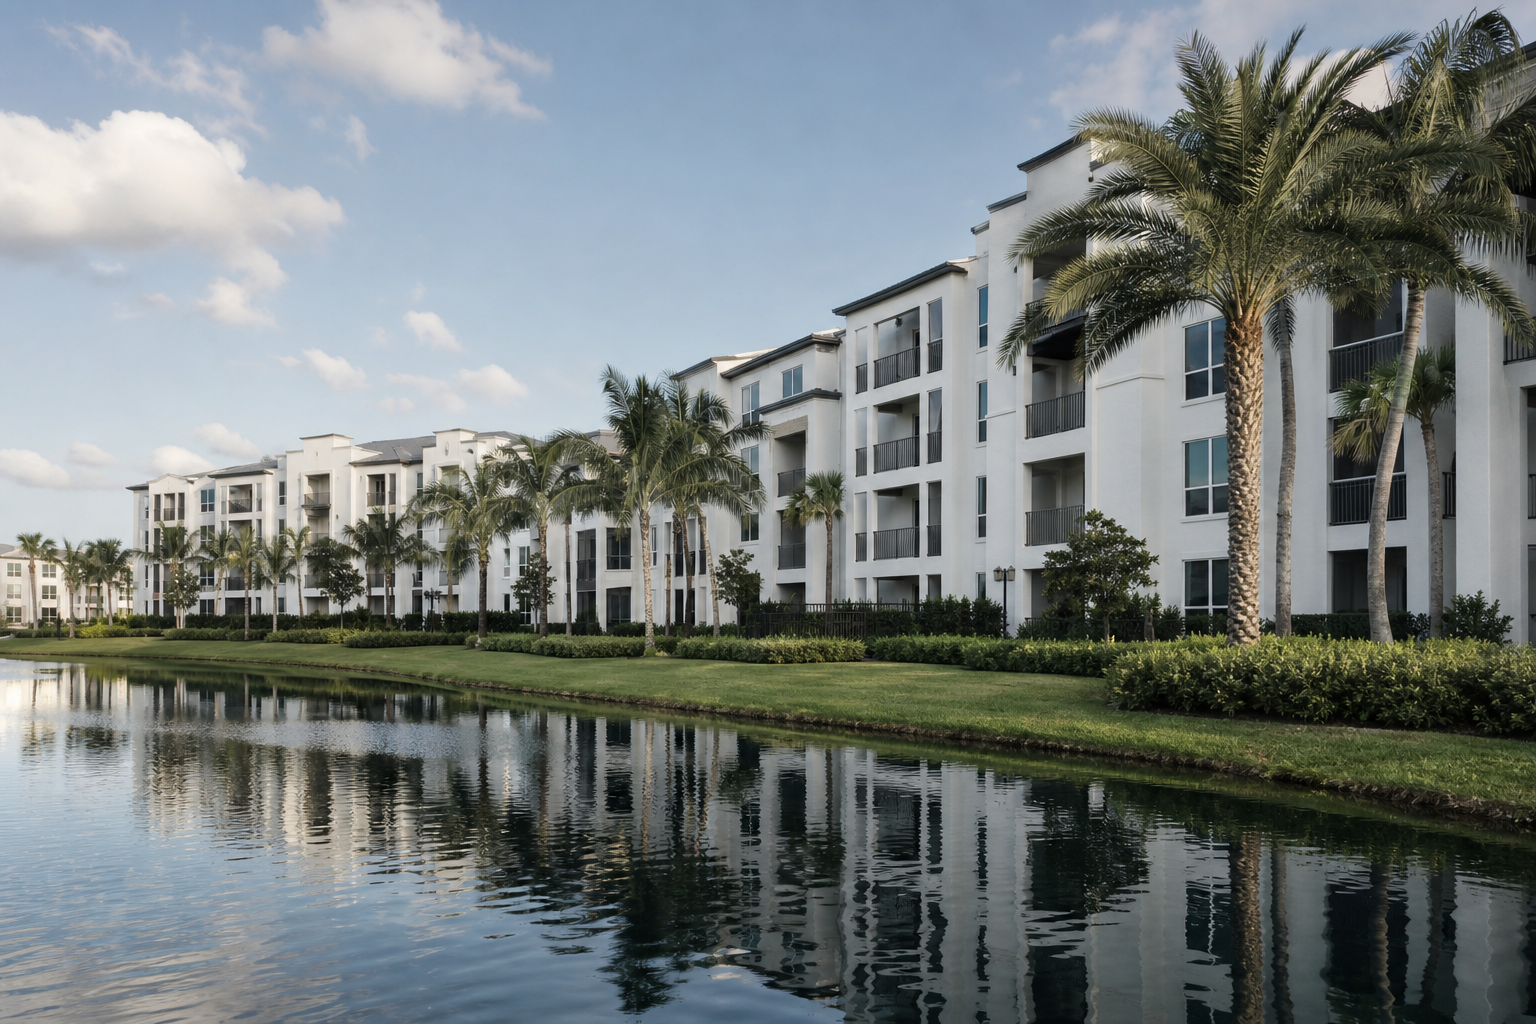
Cortland 812-unit West Palm Beach complex traded for $208M, down $21M since 2021.
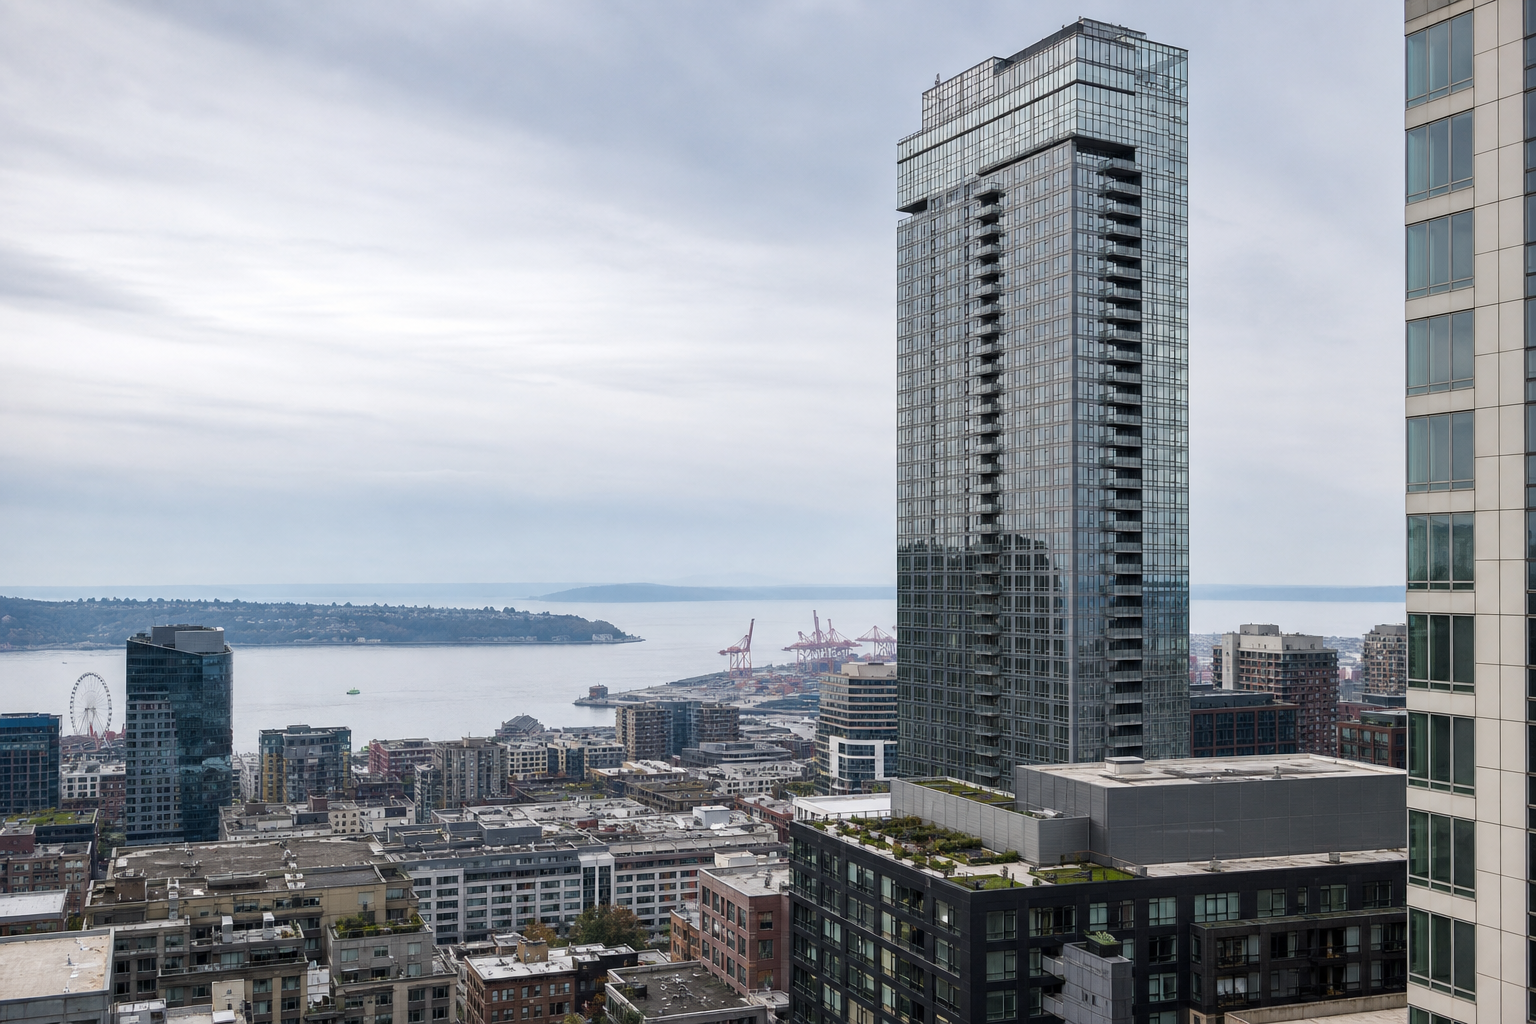
Arrive 344 Belltown units traded for $155M — floors 11 to 42 only, in the tower first sale.
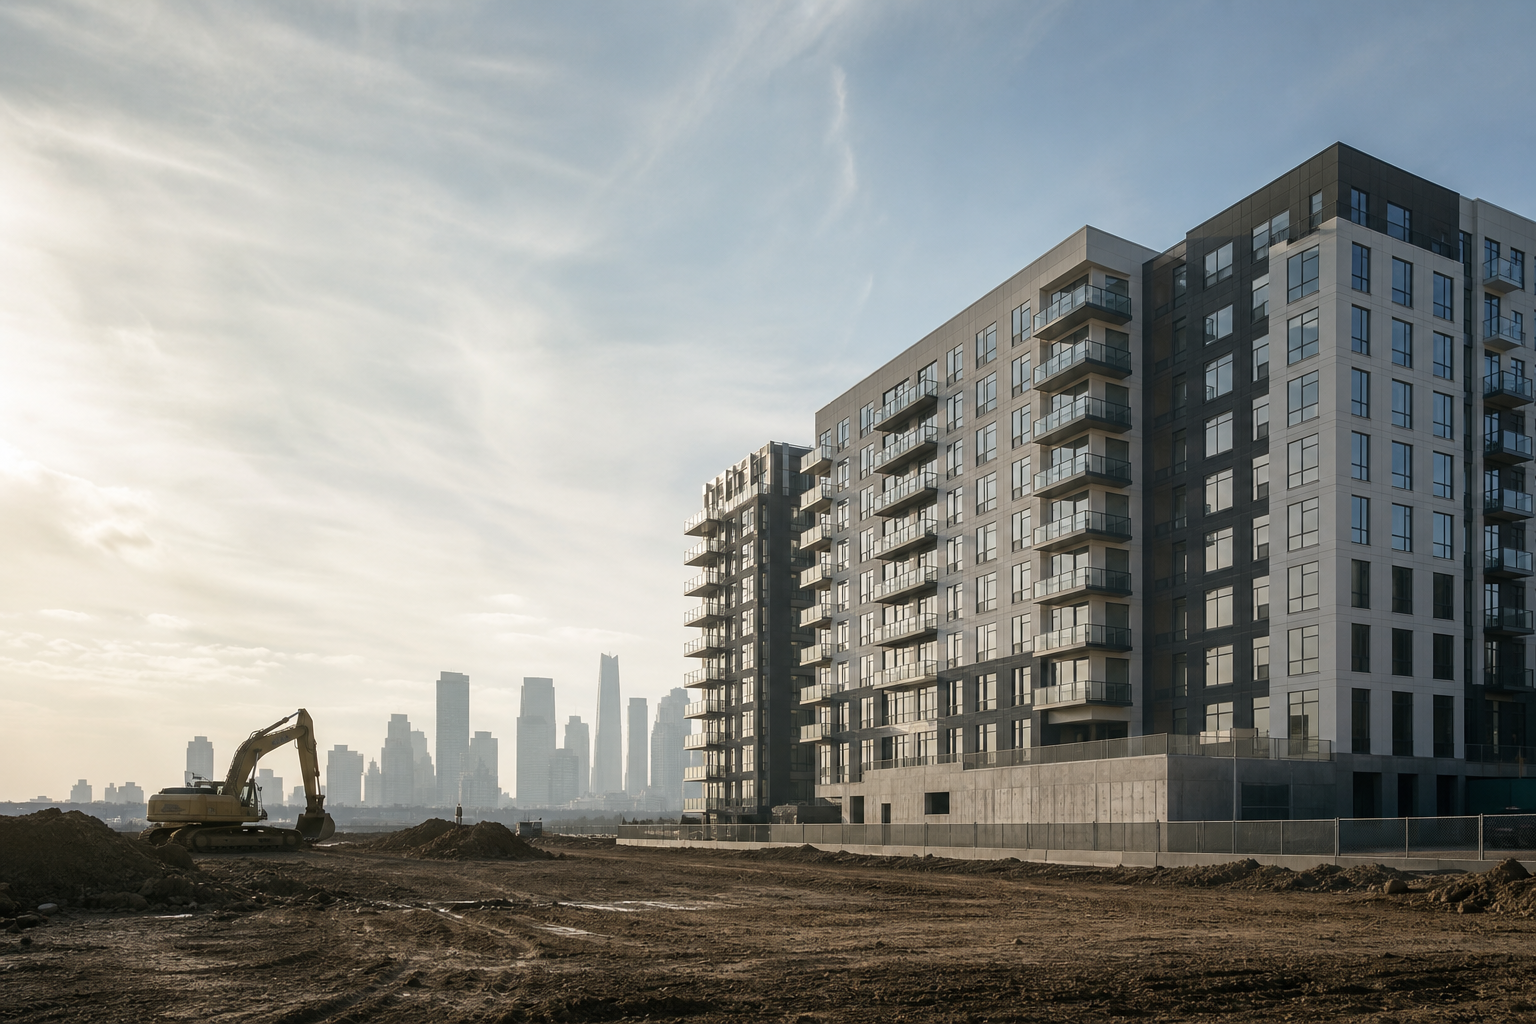
Bonaventure broke ground on 344 units without the JV — and locked the rate for four decades.
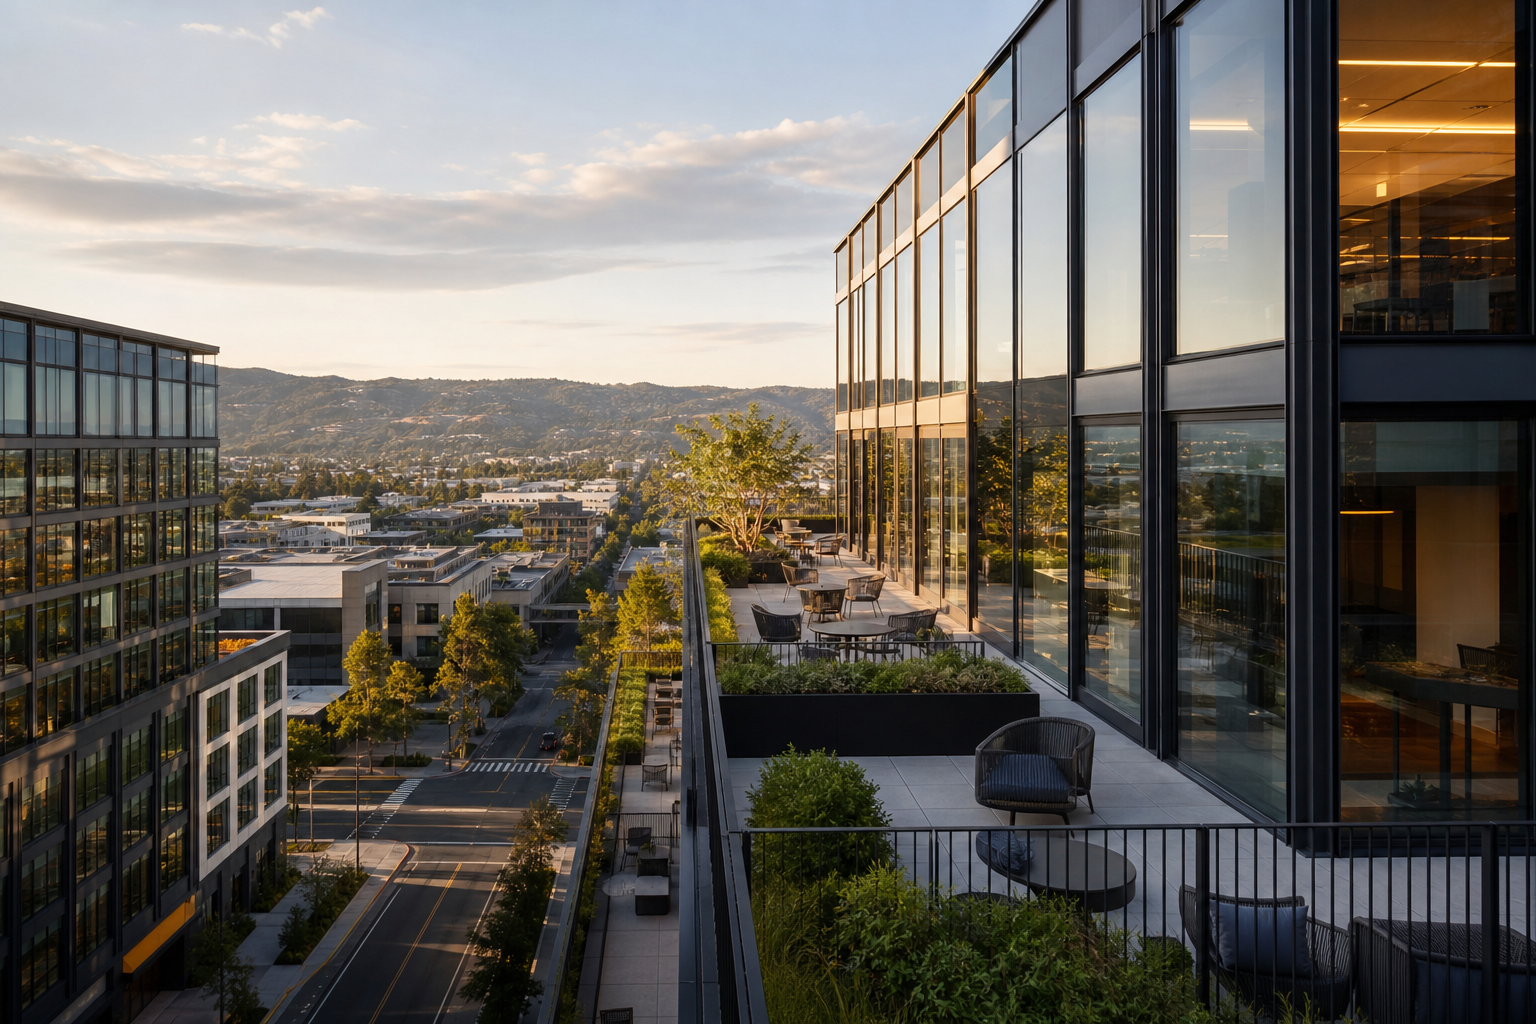
SummerHill's San Carlos project closes at $123.5M with $27M of pref behind the bank debt.
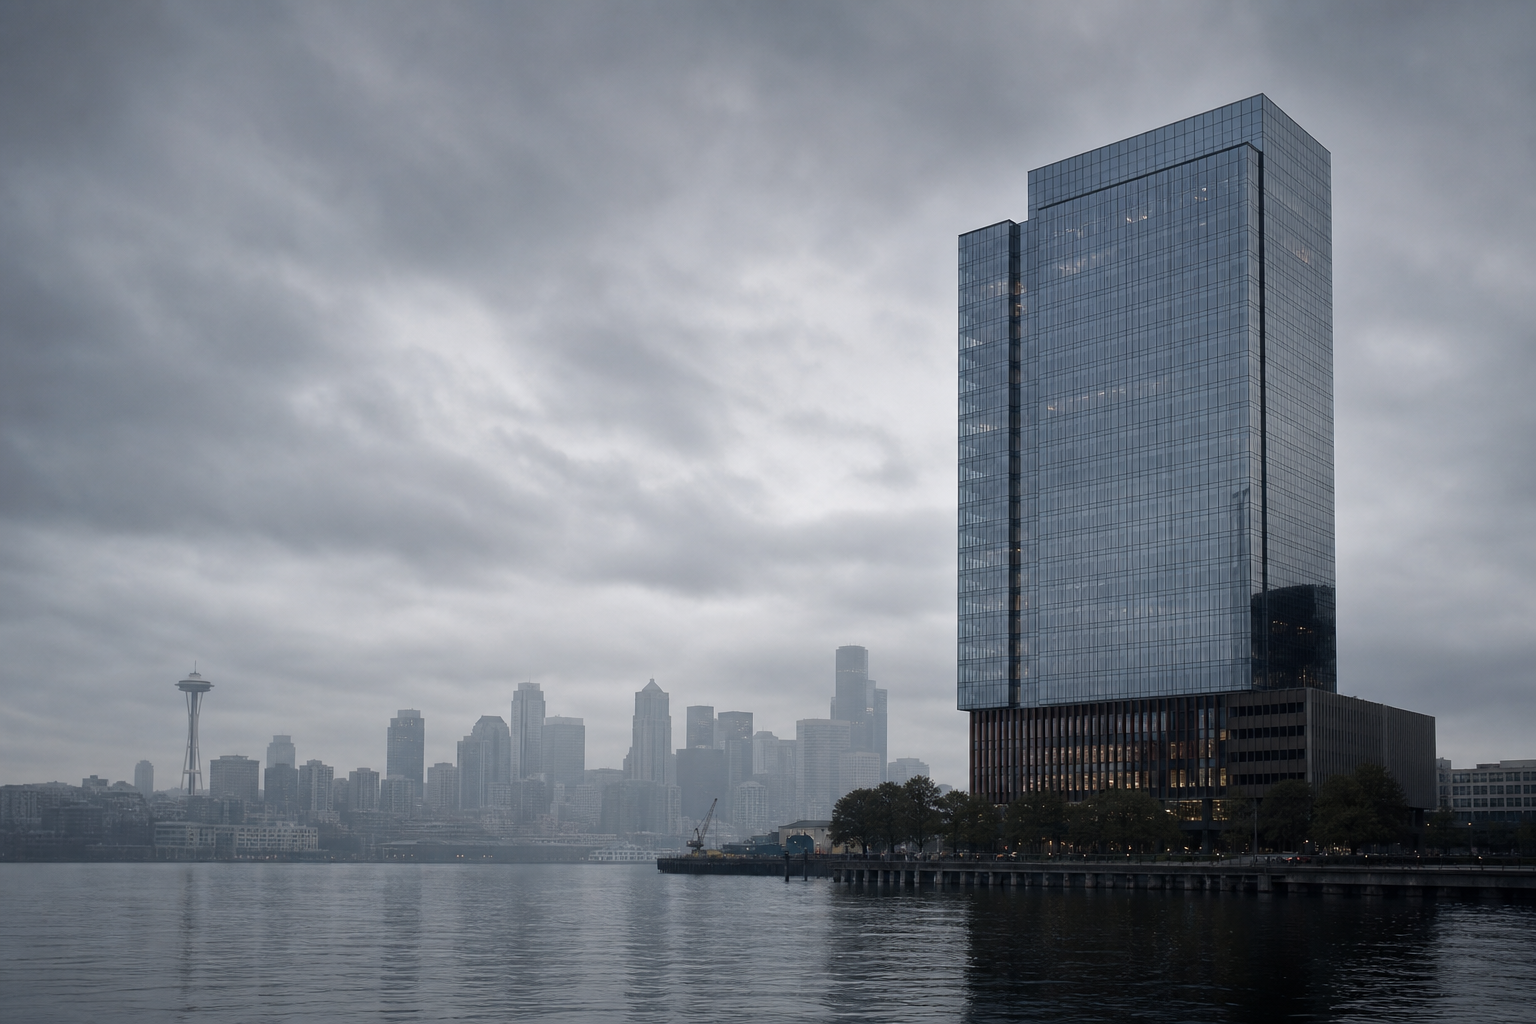
Barings put $250M on a delivered Seattle tower nine months past maturity.
Zillow paid Redfin to leave rental listings. Regulators unwound it Monday.
An analysis of 312 filings found three projects at or above 100 units. Three.
Knightvest bought three Round Rock communities at a deep discount to their peak-cycle price.
184,000 apartments under one ticker. The question is whether size pays.
Broad Creek's second close bought a 2023-built Sarasota property at roughly 213,000 dollars a unit.
A clean 211,000 dollar-per-unit trade shows institutional buyers are back in metro Phoenix.
Demand is absorbing the last of the supply wave right as the pipeline empties toward a 2027 and 2028 cliff.
Developers breaking ground now are underwriting the 2028 supply vacuum, not today rents.
A $1.63B apartment trade, the biggest since 2024, is a REIT rotating out of an entire state.
Kamson bought a converted-back rental complex, supply created without a single new foundation.
Berkshire took a nominal loss to exit a 560-unit Franklin deal to Waterton.
Starts dropped to 55,000 units, the fewest since 2011, setting up a 2027 supply drought.
A clean institutional sale at $217,500 a unit says the Southwest apartment bid is working again.
Fort Collins gets a luxury rental start as Mountain West supply thins.
Entity-level volume up 11% to $1.6B as cap rates hold near 5.7%.
Mill Creek starts 330 units in Phoenix as Morgan breaks ground on a Deerfield Beach waterfront.
M&T backs a just-built 194-unit Turtle Bay tower into lease-up.
Greystar exits a 423-unit complex at $510K a door as Goldman and GID buy the same submarket the same day.
Renter demand hit a near-25-year high as the construction pipeline empties out.
Camden pays $89.3M for 343 units in one of the most oversupplied metros — a bet the bottom is in.
Starts have collapsed to a 2017 low, yet absorption fell faster, complicating the recovery call.
Demand outpaced new supply for the first time since 2022, and the pipeline is the thinnest since 2013.
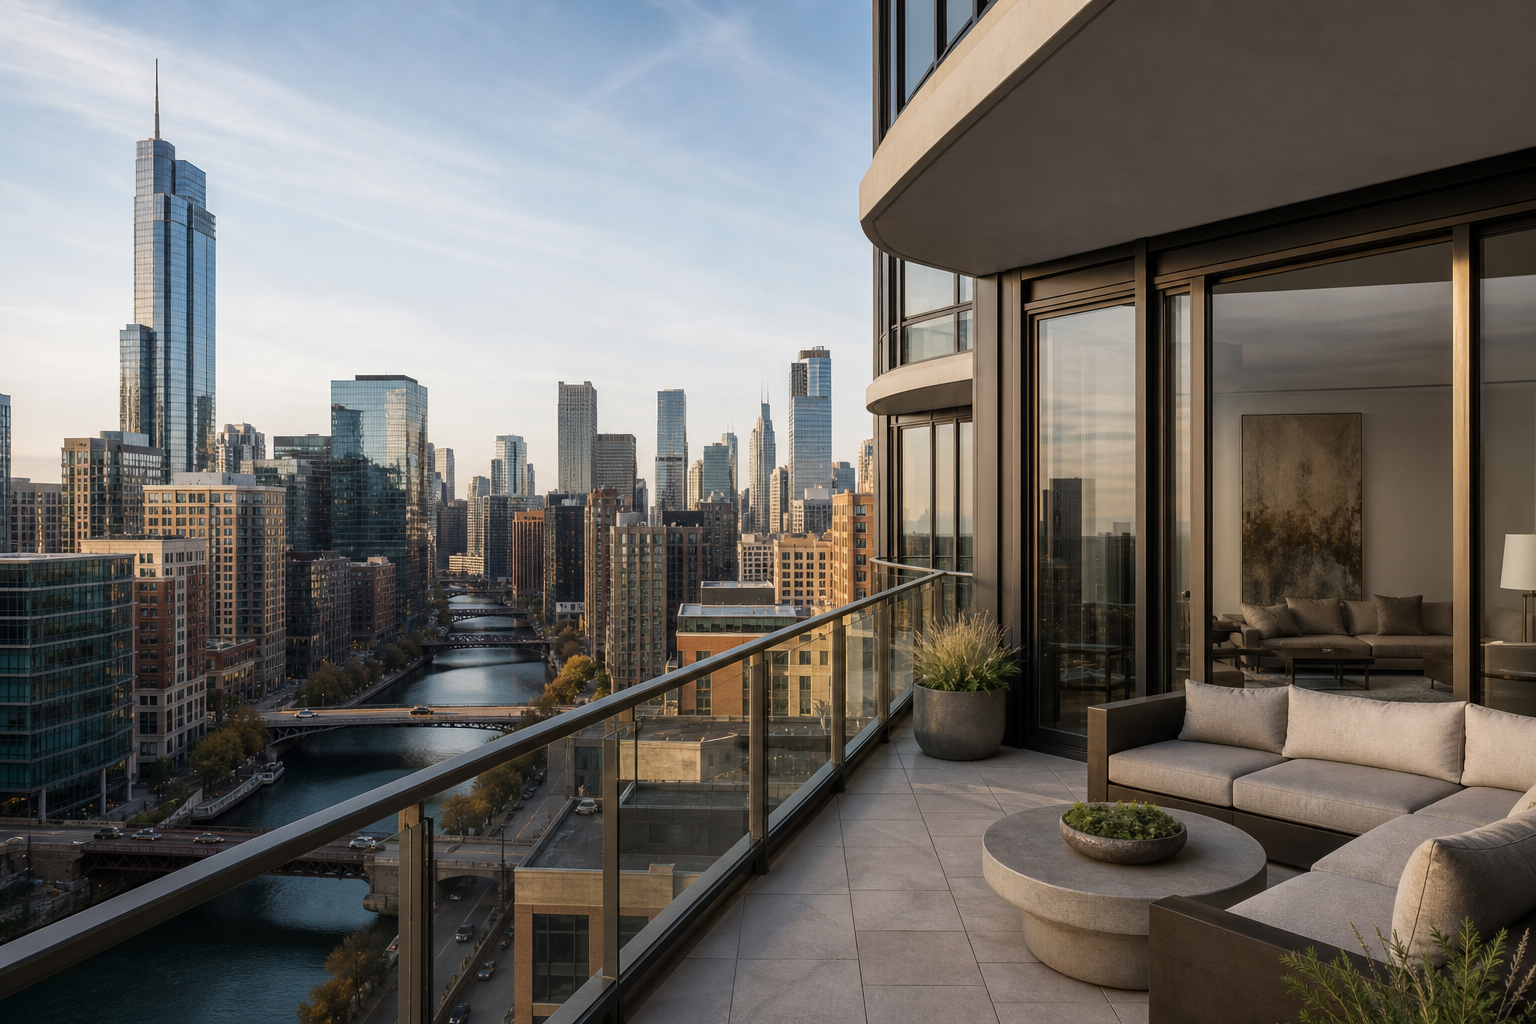
A trophy Chicago apartment trade shows the bid for the best urban product never left.
Dwight's record $183M construction loan funds new supply — exactly as national deliveries dry up.
Renters absorbed 187,000 units in Q2 as deliveries fell below the decade norm for the first time in three years.
National multifamily is stabilizing on paper — but the Sun Belt is still correcting hard underneath.
LA permitting jumps 85% while Sun Belt deliveries fall off a cliff.
Kennedy Wilson and two Japanese partners pay $237M for a Westchester Class A community.
National rent barely moved in May while the highest-supply metros posted another year of declines.
Five months of gains couldn't lift national occupancy off its weakest reading since 2013.
90,300 conversion units are in the 2026 pipeline, up 28% in a year and nearly four times the 2022 total.
Manhattan leads at 6.8% even as 4.4%-plus bond yields squeeze NY underwriting.
Units under construction dropped to 720K, down nearly 20% year-over-year.
Obsolete office is now nearly half the national adaptive-reuse pipeline
New Mountain Capital is paying $2B+ for Asset Living — a manager, not a landlord.
National rents edged up in May; Austin still prints −5.2% as Sun Belt supply clears slowly.
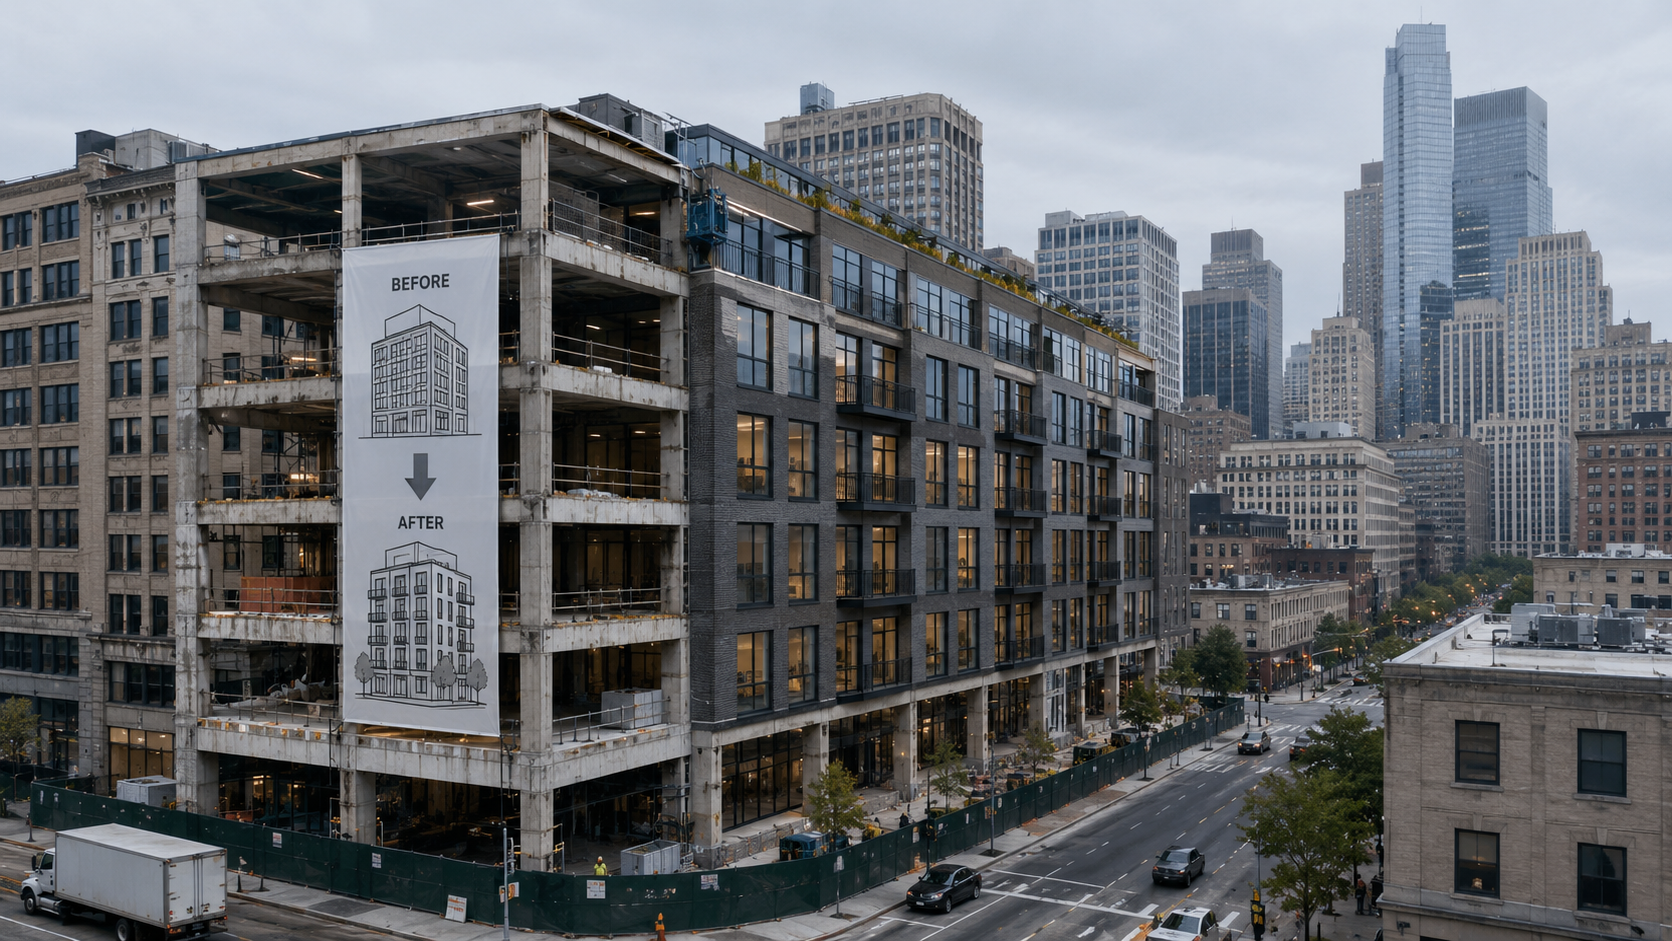
Conversions hit an all-time high in 2026 — and office is now the majority of all U.S. adaptive reuse.
Agency loan caps jump ~20% for 2026 — deeper liquidity, but routed to the deals Washington wants
DC's complaint against MAA puts ancillary fee income — the quiet driver of REIT NOI growth — under direct legal attack.
AVB and EQR confirm early discussions on a ~$50B combination that would reset Class A coastal multifamily.
Demand cools after a strong run, but muted construction and shrinking pipelines prevent oversupply, creating a near-term stabilization window for multifamily assets.
Rapid population growth, led by DFW, is reshaping strategies for large-scale residential development and planning.
State and local policy changes tighten compliance, strengthen tenant protections, and reshape operational standards.
Section 2924.13 sparks lawsuits, challenging the balance between foreclosure reform and established contracts.
Agency lending capacity rises as federal housing priorities remain firmly anchored.
Early-year sale highlights durable bid-side demand for stabilized suburban rentals
Fluctuations in advertised rents and leasing activity are challenging long-held assumptions about rental resilience.
Growing student debt and affordability gaps are redefining when—and how—younger generations enter the housing market.
Cash Flow-Based Lending Reshapes Qualification
Occupier Financial Behavior Signals Changes in Property Use and Market Dynamics
The Kansas City Current names its mixed-use waterfront district, targeting first openings in spring 2026 near CPKC Stadium.
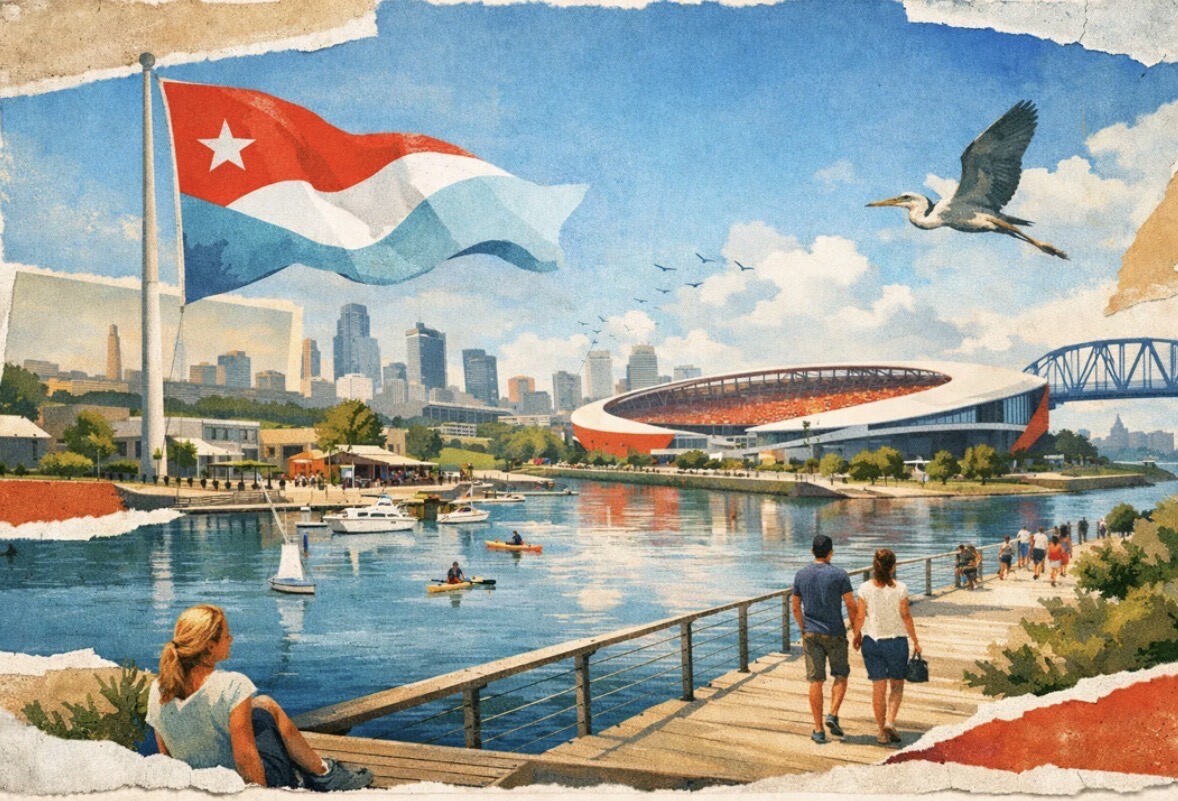
The Kansas City Current names its mixed-use waterfront district, targeting first openings in spring 2026 near CPKC Stadium.
Three consecutive months of sales growth signal changing household purchase behavior.
Seasonal declines and evolving listing patterns highlight changing dynamics for future housing availability.
Interest in fifty-year loans highlights how borrowers are adapting to persistent affordability barriers.
Renewal behavior and stable occupancy point to sustained renter commitment despite shifting market conditions.
Policymakers are reassessing whether legacy benchmarks still align with modern renter financial realities.
Resident behavior in the metro is diverging from national trends, reshaping pricing power and absorption dynamics.
Stable mortgage rates and rising applications signal sustained buyer interest.
Evolving demand patterns and limited new supply are pushing institutions to reset assumptions across key property sectors.
Changing rate incentives and rising retention trends highlight evolving engagement patterns across the mortgage landscape.
Mortgage activity, inventory shifts, and pricing patterns reveal evolving buyer behavior.
FTC and Colorado force the nation’s largest property manager to disclose full lease pricing upfront — signaling a broader crackdown on opaque fee structures in multifamily.
Guidance cuts, uneven rent growth, and shifting tenant patterns raise new questions about where multifamily performance goes from here.
As markets shift and buyers change, companies are discovering that culture—not perks—quietly determines performance, customer trust, and long-term competitiveness.
Soft absorption, weaker rent growth, and shifting resident behavior signal that the multifamily cycle may be entering a subtler, more complicated phase.
A sharp slowdown in permits, absorption, and lease-ups hints at a market entering recalibration—and a supply gap forming for 2026.
Transitional forces suggest an environment where demand will be redefined by new patterns of activity.
Variations in borrower activity illustrate how demand adapts to a landscape shaped by economic and lending influences.
Forecasted shifts in demand reflect broader adjustments in market dynamics as inventory and purchasing power slowly recalibrate.
Financial resources act as a catalyst for shaping organizational direction in specialized real estate sectors.
As homeowners choose to invest in current properties instead of moving amid high mortgage rates.
Construction-loan discipline is filtering projects faster than demand trends.
Rental ‘junk fee’ reforms force underwriting shifts and transparency upgrades across U.S. multifamily sector as operators adapt to patchwork rules.
Surging insurance premiums, flat rents, and regulatory friction upend cash flows and asset sustainability for New York City’s legacy affordable housing.
Life insurers back select large multifamily loans as capital clusters around stabilized assets, signaling a two-speed Florida market.
Institutional Capital Expands in Student Housing with Multi-Metro $1B Acquisition
Election result could redefine multifamily and commercial real estate landscape in NYC.
National rents fall 0.8% in October as new supply surges; multifamily operators shift from growth to preservation
Four attorneys general move to block a $141 million rent-fixing settlement, signaling broader regulatory risk for multifamily underwriting.
Large-check capital goes granular as portfolios freeze and sector rotation reshapes U.S. CRE allocation.
Large-Cap Buyers Reprice and Re-Enter NYC Office
GIC and ADIA’s $1.1 billion refinance of Deutsche Bank Center restores confidence in trophy-grade CMBS execution.
Disciplined fundamentals sustain absorption as rent growth cools and capital flows persist.
Tight vacancies, record tourism, and global capital define Florida’s CRE cycle
As rents post their steepest fall in 15 years, capital tightens underwriting standards and resets yield expectations.
A major Queens portfolio default exposes the structural fragility of New York’s regulated multifamily credit.
Multifamily rents stall as 475k new units hit the market, driving concessions and soft occupancy.
Exploding construction costs force Miami developers to reprice projects, rethink feasibility, and cap leverage.
Record-pace leasing and falling vacancies mark a decisive Class A recovery in Manhattan office demand.
Venezuelan outflows trigger vacancies in Doral, accelerating Florida’s broader multifamily rent plateau.
2024’s record deliveries pushed vacancies to ~12%, but with new supply plunging 50%, Texas multifamily is stabilizing fast.
Investors pivot from secondary retail toward AI, ESG-compliant assets as capital reallocates globally.
High-end housing faces thinning buyers, forcing repricing and longer absorption timelines.
Landmark deal curbs algorithmic rent setting, reshaping underwriting and tenant retention in multifamily.
Vacancy rises modestly, but strong demand and record permits keep Northwest Arkansas resilient against U.S. market slump.
Debt funds and CMBS re-open the channel, easing execution for qualify-to-close CRE.
Bankruptcy sale of Pinnacle’s rent-stabilized portfolio resets NYC underwriting and lender recoveries.
Rent burdens and supply shortfall strain multifamily investors despite Fed rate cuts.
Oversubscribed raise underscores institutional appetite for value-add multifamily despite higher rates.
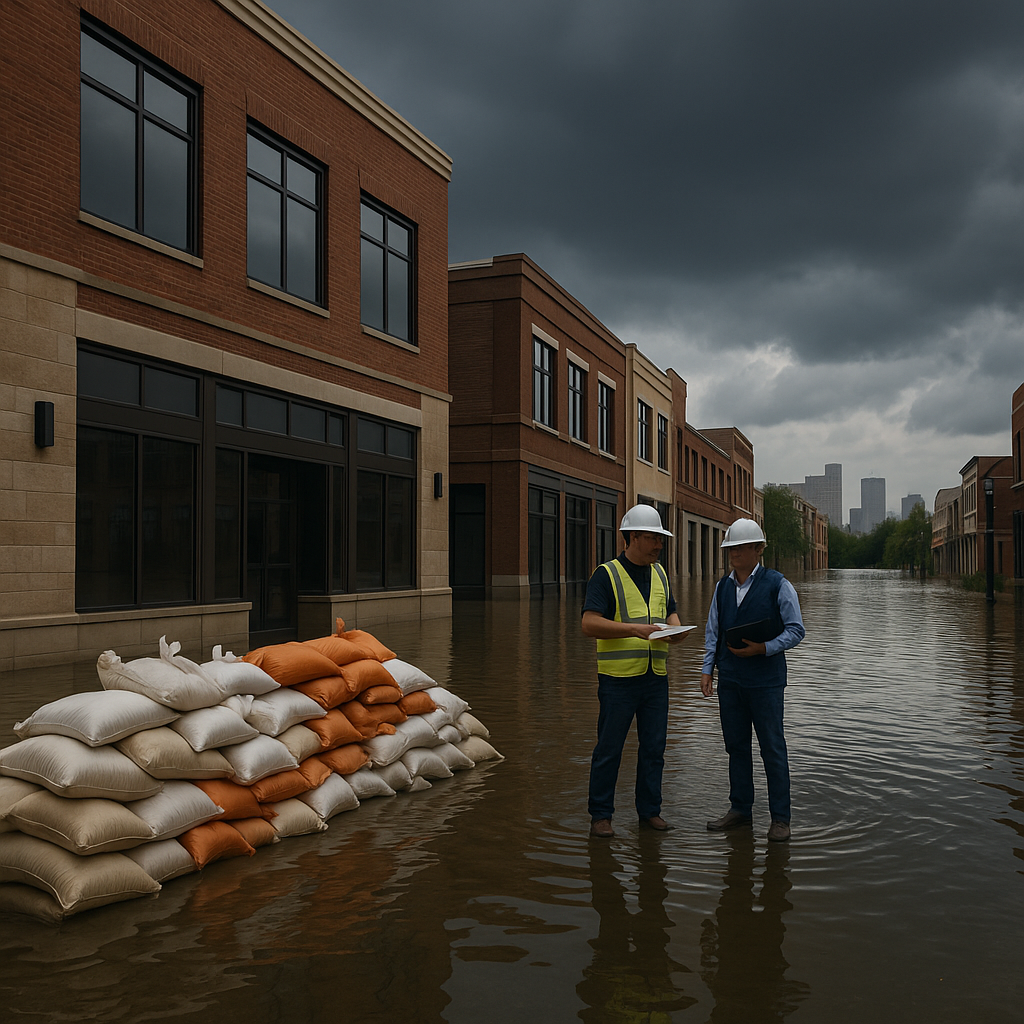
Insurance premiums up 88% in 5 years, $1.4T in real estate at risk. Climate resilience moves from ESG talk to underwriting math.
Easing base rates lower agency coupons and bridge carry, nudging DSCR over the line in stabilized markets.
Cooling permits and a thinning MF pipeline ease 2026 supply pressure—supportive for rent stabilization in overbuilt nodes.
Portfolio transfer highlights capital rotation into multifamily as developers retreat and long-term operators expand.
Toll exits rentals, Kennedy Wilson gains $5B pipeline — a late-cycle bet on multifamily resilience.
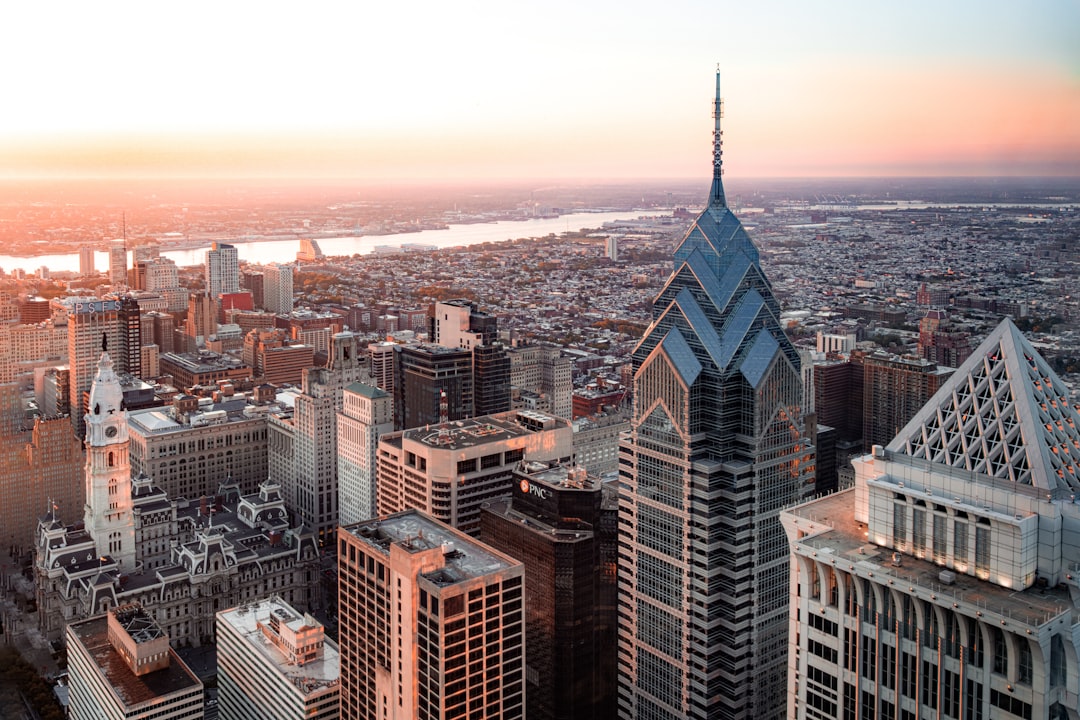
Brookfield’s $400 million revamp fills 660 Fifth, highlighting NYC's flight-to-quality in office leasing.
Increased supply curbs rent growth, impacting multifamily returns in high-growth markets.
Multifamily and data centers thrive amid rising office delinquencies; tailored strategies are crucial.
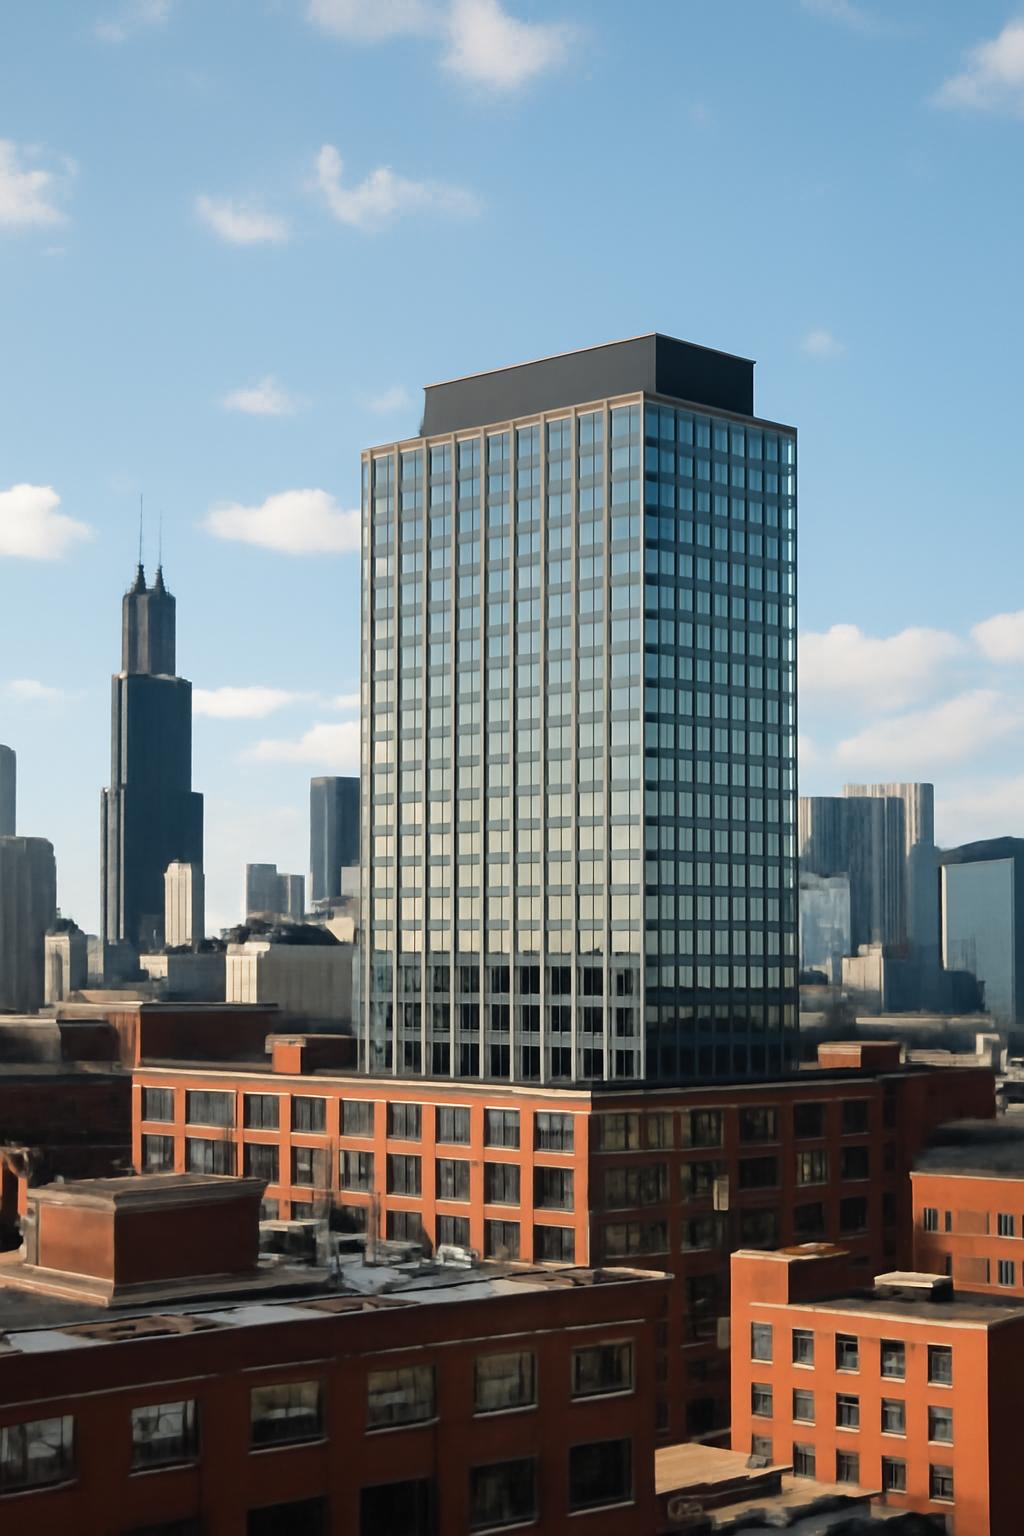
Fulton Market trade shows cap-rate stability as rent growth reopens bid-ask spreads.
Fresh equity targets Sunbelt apartments as debt maturities bite.
Over $1B multi-asset refinance across Southern California & Hawaii
Owners consolidate and upsize debt on twin luxury towers, locking long-term financing well before maturities hit..
U.S. apartment rents fell again in August, as 950k new units under delivery push vacancies higher and blunt landlords’ pricing power.
CMBS delinquencies rose for the sixth straight month to 7.29% in August. Office hit a record 11.66% and multifamily climbed to a nine-year high at 6.86%, tightening credit and accelerating workouts.
U.S. rents fell in August as deliveries peaked. Supply-heavy Sun Belt metros are contracting while supply-constrained coasts and the Midwest hold up. 09/2025. Sources: CoStar
The under-construction pipeline has fallen ~60% from the 2023 peak to ~543k units, setting up a 2026–27 supply drought after 2025’s final wave of deliveries. Date: 09/2025. Source: RealPage Market Analytics (Q2 2025).
The nation’s largest apartment manager is rolling out pricing calculators, AI tools, and resident-facing transparency measures to sustain NOI in a cooling rental market.
U.S. multifamily market cools as rent growth stagnates at 0.7% YoY, with record supply and softening demand causing occupancy and concession shifts in 2024.
CMBS market faces mounting distress as U.S. delinquency rates hit 7.29%, with office and multifamily sectors driving record defaults amid challenging refinancing landscape.
Discover Charlotte's multifamily market resurgence: Investors return as supply peaks, rents stabilize, and opportunities emerge in this promising Sunbelt real estate landscape.
Source: RealPage, CRE Daily Recap
Source: Yardi Matrix
Date: Aug 9, 2025 | Sources: CRE Daily; Seniors Housing Business
Trusted Daily
40,000+
Daily Subscribers
Brokers, investors, developers, and lenders open CRE 360 Signal™ every morning for the market intelligence that moves their decisions.
Free. Independent. Editorially rigorous.
Follow the Signal
Add your profile URLs from the Editorial Desk → Social links.