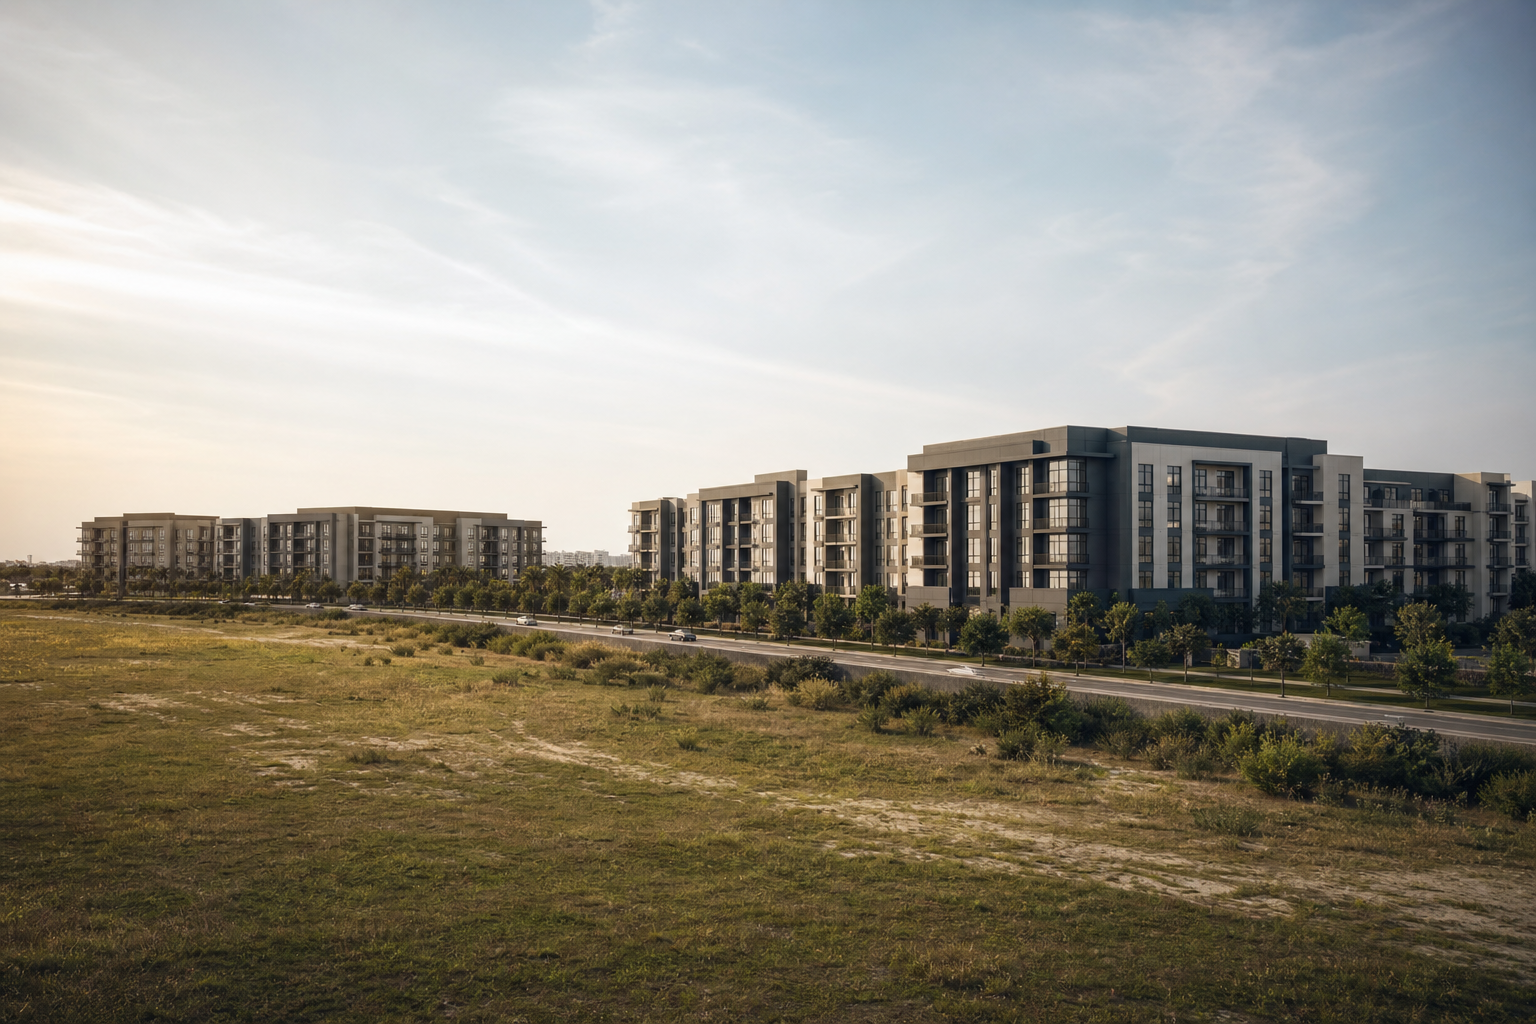
- Exchange capital is moving from stabilized net lease into ground-up Sun Belt multifamily.
- A current-pay coupon on a building two years from delivery has to be funded by someone; that someone is the sponsor.
- Senior-to-sponsor TIC equity is structurally closer to preferred equity than to ownership.
The 1031 investor's traditional product is a stabilized, credit-tenanted box with a coupon the tenant pays. This offering asks the same investor to take construction, lease-up and 2028 delivery risk for a 5.75% current return that, during construction, can only come from reserves or sponsor capital.
That is not inherently wrong. It is a repricing of who bears development risk. Sponsor equity of about $34M below a $95.3M TIC layer means the sponsor's capital absorbs the first loss on a roughly $289M stack — an inverted position relative to a typical GP/LP deal.
The $622K-per-unit implied cost is the number to anchor on. It is a high basis for Palm Beach County suburban product and requires stabilized rents that justify it in 2028–29.
The macro tailwind is real: DST inflows are up a third this year because exchange sellers are sitting on gains and short of replacement product. Sponsors are building product to meet that demand.
Implications
If exchange capital keeps flowing into development, expect more TIC/DST wrappers on construction deals across the Sun Belt. Buyers should underwrite the reserve that funds the coupon, the refinance assumption behind the capital return, and the 2029 exit cap — not the 5.75% headline. Single-origin on the raise itself; loan and TIF confirmed by multiple outlets.
Key Takeaways
- A 5.75% coupon on a building that doesn't exist is a sponsor-funded promise, not a yield.
- Senior-to-sponsor TIC equity behaves like preferred equity with development risk attached.
- Underwrite the coupon reserve and the refinance assumption, not the headline return.
AltsWire, Sept 11, 2026 — Time Equities launches $95.3M TIC offering for Florida multifamily project · Commercial Observer, April 2026 — $160M M&T-led construction loan for OCTAVIA, Boynton Beach · Multi-Housing News, April 2026 — OCTAVIA construction financing and $20M TIF · Mountain Dell via AltsWire, Sept 8, 2026 — DST fundraising $6.48B through August, +33% YoY
Never miss a Signal
Get the daily brief that busy CRE professionals rely on.