Key Highlights
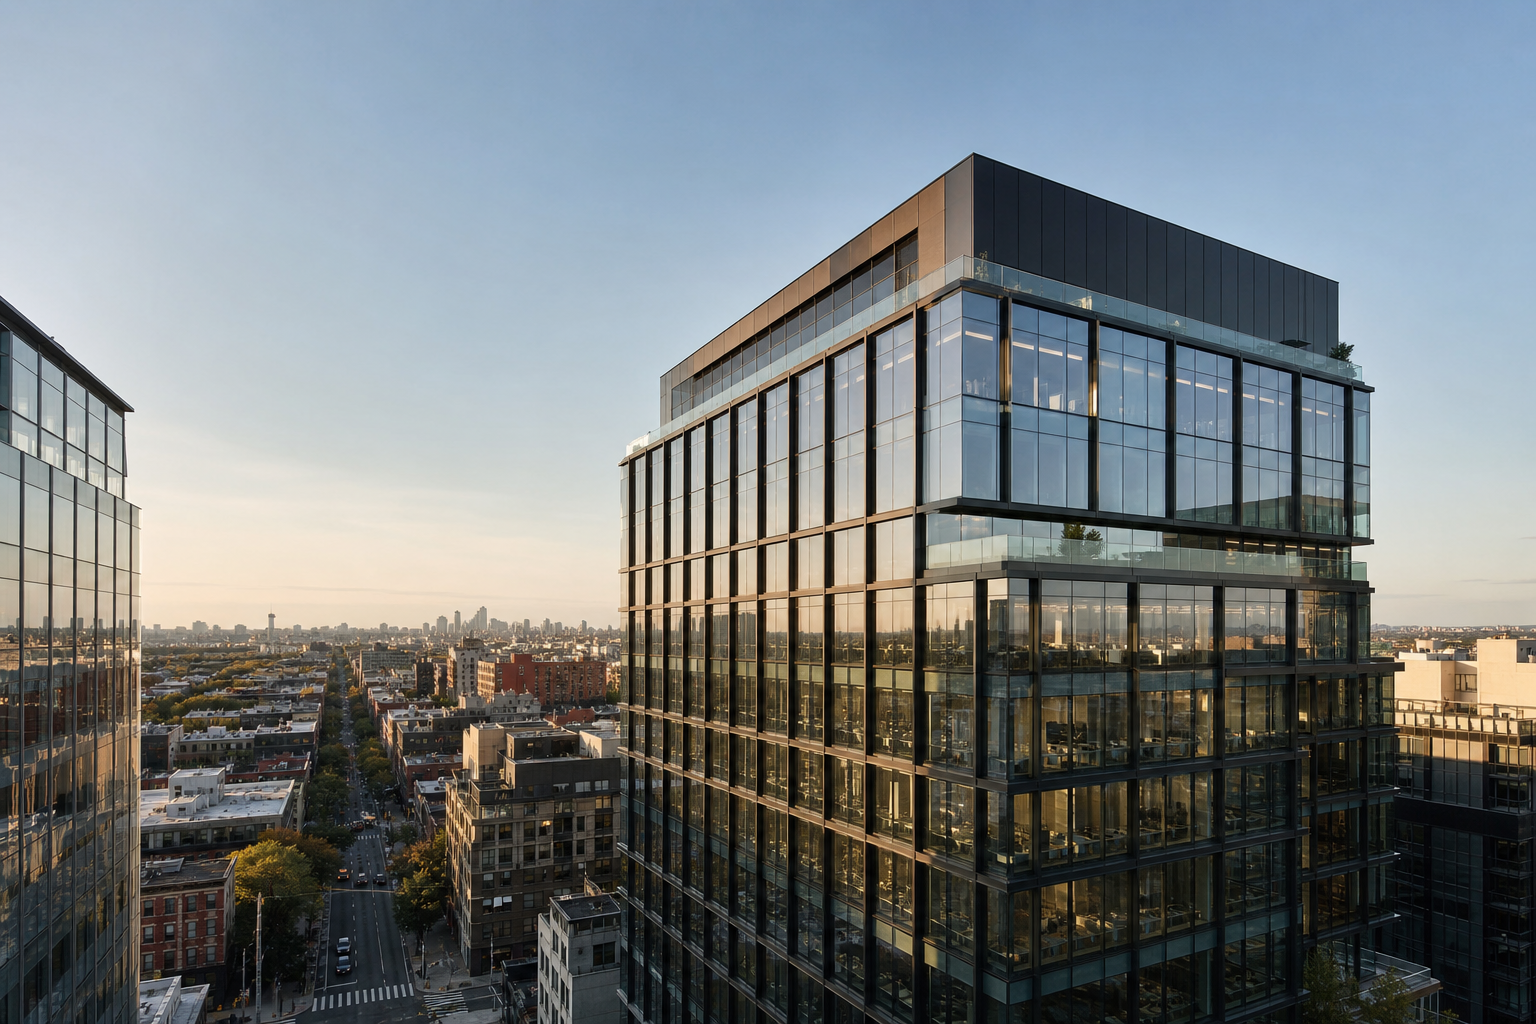
- Corebridge Financial provided a $293M fixed-rate permanent loan on 40 Tenth Avenue, a 158,957-sf, 2019-built office-and-retail building in the Meatpacking District.
- The loan retires a $150M 2020 construction loan from Deutsche Pfandbriefbank — a 95% increase in debt on the same asset in six years.
- The building is fully leased; office tenants include Starwood Capital Group, WestCap, RTW Investments, Stripes and Checkout.com; Hyundai anchors the retail.
- Borrower: a joint venture of Aurora Capital Associates and William Gottlieb Real Estate. Walker & Dunlop's Dustin Stolly, Aaron Appel and Jonathan Schwartz arranged the debt.
- Implied leverage: roughly $1,843 per square foot of debt on a 112,241-sf office component plus 46,176 sf of retail.
The Signal
- Permanent, fixed-rate, life-company money on office at $1,800+ per foot only happens when the rent roll is treated as investment-grade credit.
- This is the opposite end of the same market that just reappraised Denver's tallest tower at 59 cents.
- Boutique, new-build, fully leased, High Line-adjacent: every attribute is a screen, and the loan proves the screen clears at scale.
What is happening: a life insurer just took out a bank construction lender on a Manhattan office asset at nearly twice the original loan amount, on fixed-rate permanent terms. That is a bet on the leases, not on the office market.
Why it matters: since 2023 the standard read has been that permanent office debt is unavailable outside trophy Park Avenue towers. 40 Tenth Avenue is 158,957 sf, not 1.5 million. The loan shows insurers will lend big on small, new, fully leased buildings with hedge-fund and fintech tenancy — the credit lens has replaced the size lens.
The basis math: $150M of construction debt in 2020 becoming $293M of permanent debt in 2026 implies the lender is underwriting value well above $400M at conventional life-company leverage, for a building delivered seven years ago. That is a valuation move most office owners have not seen in this cycle.
What the sponsor did: Aurora and Gottlieb held the asset through delivery, leased it to credit tenants, and refinanced into duration. The playbook is not complicated; it just requires a building tenants actually want.
Caution: rate, term and amortization were not disclosed. The 95% debt increase reflects a mix of value creation and cash-out, and the split is unknown.
Implications
- For owners of new-build, fully leased, sub-200K-sf office: life-company permanent debt is open. Bring the rent roll.
- For owners of everything else: the spread between this loan and the Denver mark is the cost of an unleased floor plate.
- For construction lenders: Pfandbriefbank got taken out at par plus; that is the exit case that keeps office construction lending alive at all.
Office debt did not disappear; it moved to buildings where the tenant roster reads like a credit memo.
Key Takeaways
- Permanent, fixed-rate, life-company money on office at $1,800+ per foot only happens when the rent roll is treated as investment-grade credit.
- This is the opposite end of the same market that just reappraised Denver's tallest tower at 59 cents.
- Boutique, new-build, fully leased, High Line-adjacent: every attribute is a screen, and the loan proves the screen clears at scale.
- Office debt did not disappear; it moved to buildings where the tenant roster reads like a credit memo.
Commercial Observer — Corebridge Financial Refis Meatpacking Office Property With $293M Loan (Sept 18, 2026) — https://commercialobserver.com/2026/09/corebridge-40-tenth-avenue-meatpacking-district-office/ · Connect CRE — Fully Leased Meatpacking District Mixed-Use Refinanced for $293M — https://www.connectcre.com/stories/fully-leased-meatpacking-district-mixed-use-refinanced-for-293m/ · Walker & Dunlop — Arranges $293M Refinancing for Mixed-Use Property in Manhattan's Meatpacking District (Sept 17, 2026)
Never miss a Signal
Get the daily brief that busy CRE professionals rely on.