-12.1% against the 2004 purchase price alone, over 22 years. -61.6% against all-in basis of roughly $64.6M. $639,604 per unit all-in versus $245,545 per unit realized.
A REIT sold a Los Angeles waterfront apartment asset for less nominal dollars than it paid during George W. Bush's first term — after spending $360,396 per unit improving it.
The reflex is to read that as a Los Angeles multifamily mark. It is not. The dominant variable is the ground lease. A 41-year remaining term is short enough that the residual is compressing every year and long enough that a buyer still has to underwrite four decades of operations. That combination narrows the buyer pool to specialists and prices the asset off a wasting-asset curve, not a cap rate.
Which is exactly why the capex line matters more than the price. Essex spent $36.4M improving a leasehold it did not own the dirt under. Those dollars had to earn back inside a shrinking term, and the exit says they did not.
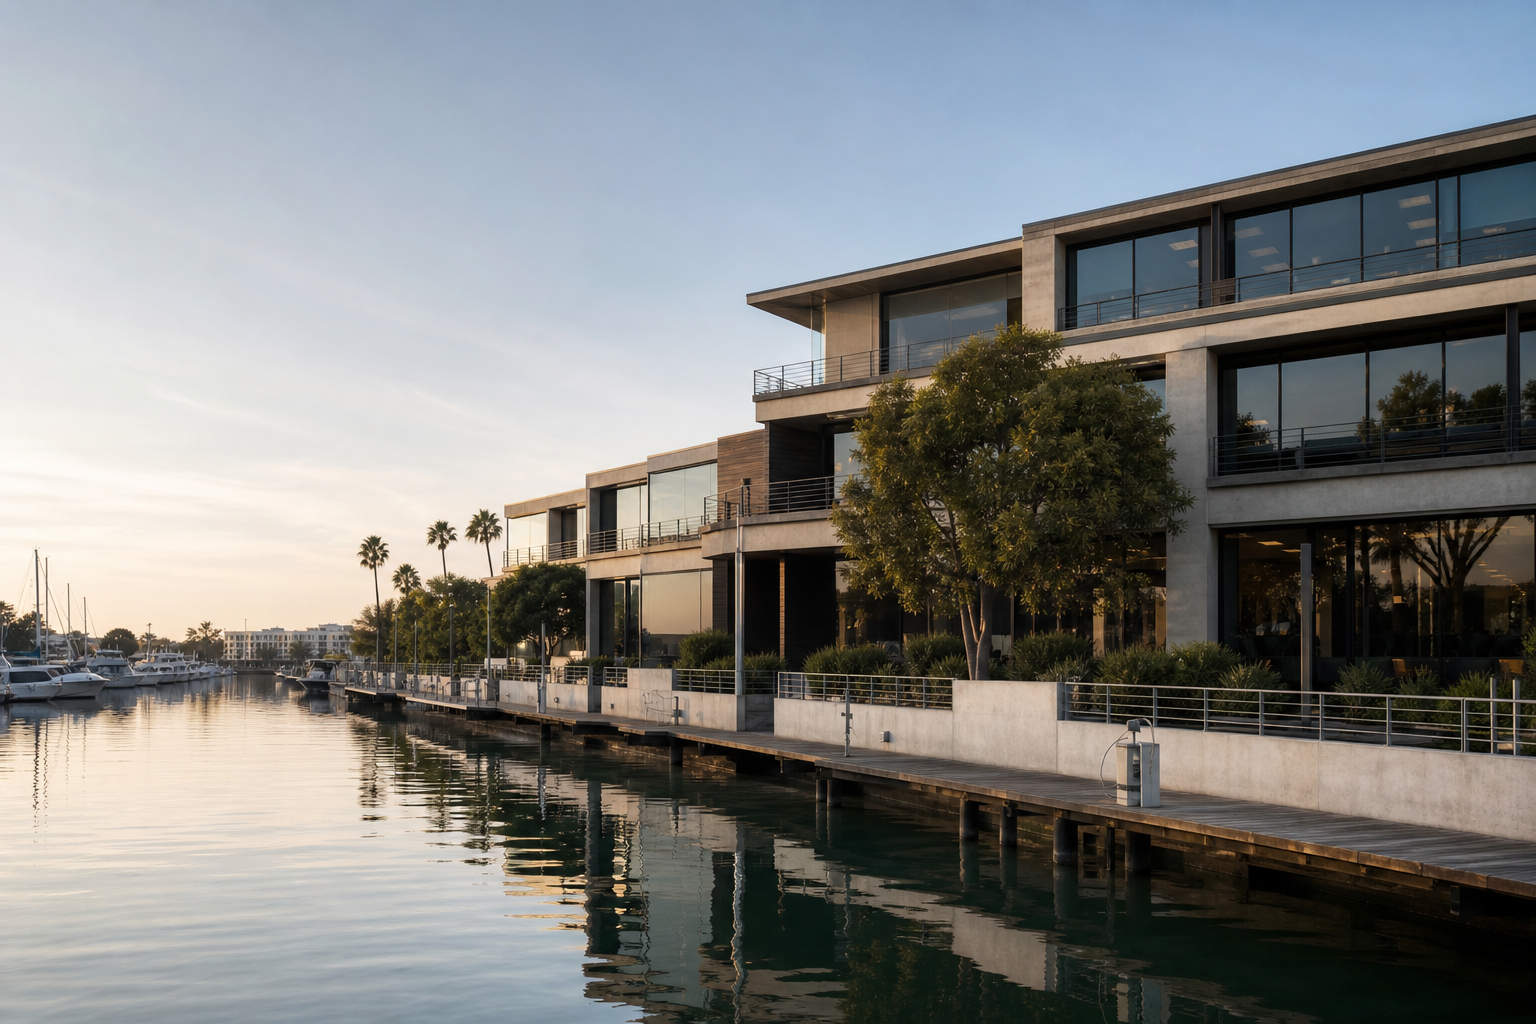
The Marina City Club setting — 600 condos, 30,000 sf of commercial, 303 boat slips — makes the asset harder still. A rental block inside a condo regime shares governance it does not control.
Implications. A leasehold is not a discount to fee simple. It is a different instrument with its own decay schedule. Capital spent on one has a hard deadline the underwriting has to name explicitly, and improvements made in year 20 of a 63-year lease are amortizing against a term the owner cannot extend unilaterally.
Uncertainty: price and 2004 basis come from public records and Essex SEC filings, not a party release. The deed-recording date is not stated and may predate September 7. This is a leasehold-decay mark, not a clean market mark for Los Angeles multifamily.
Related coverage
Key Takeaways
- On a leasehold, capex has an expiration date — and the ground lease, not the market, sets it
- Essex realized -61.6% against all-in basis and -12.1% against its 2004 purchase price alone
- $360,396 per unit of capital improvements had to amortize inside a term the owner could not extend
Multi-Housing News, September 7, 2026 · Public records and Essex Property Trust SEC filings · Per-unit and percentage figures derived by CRE360
Never miss a Signal
Get the daily brief that busy CRE professionals rely on.