

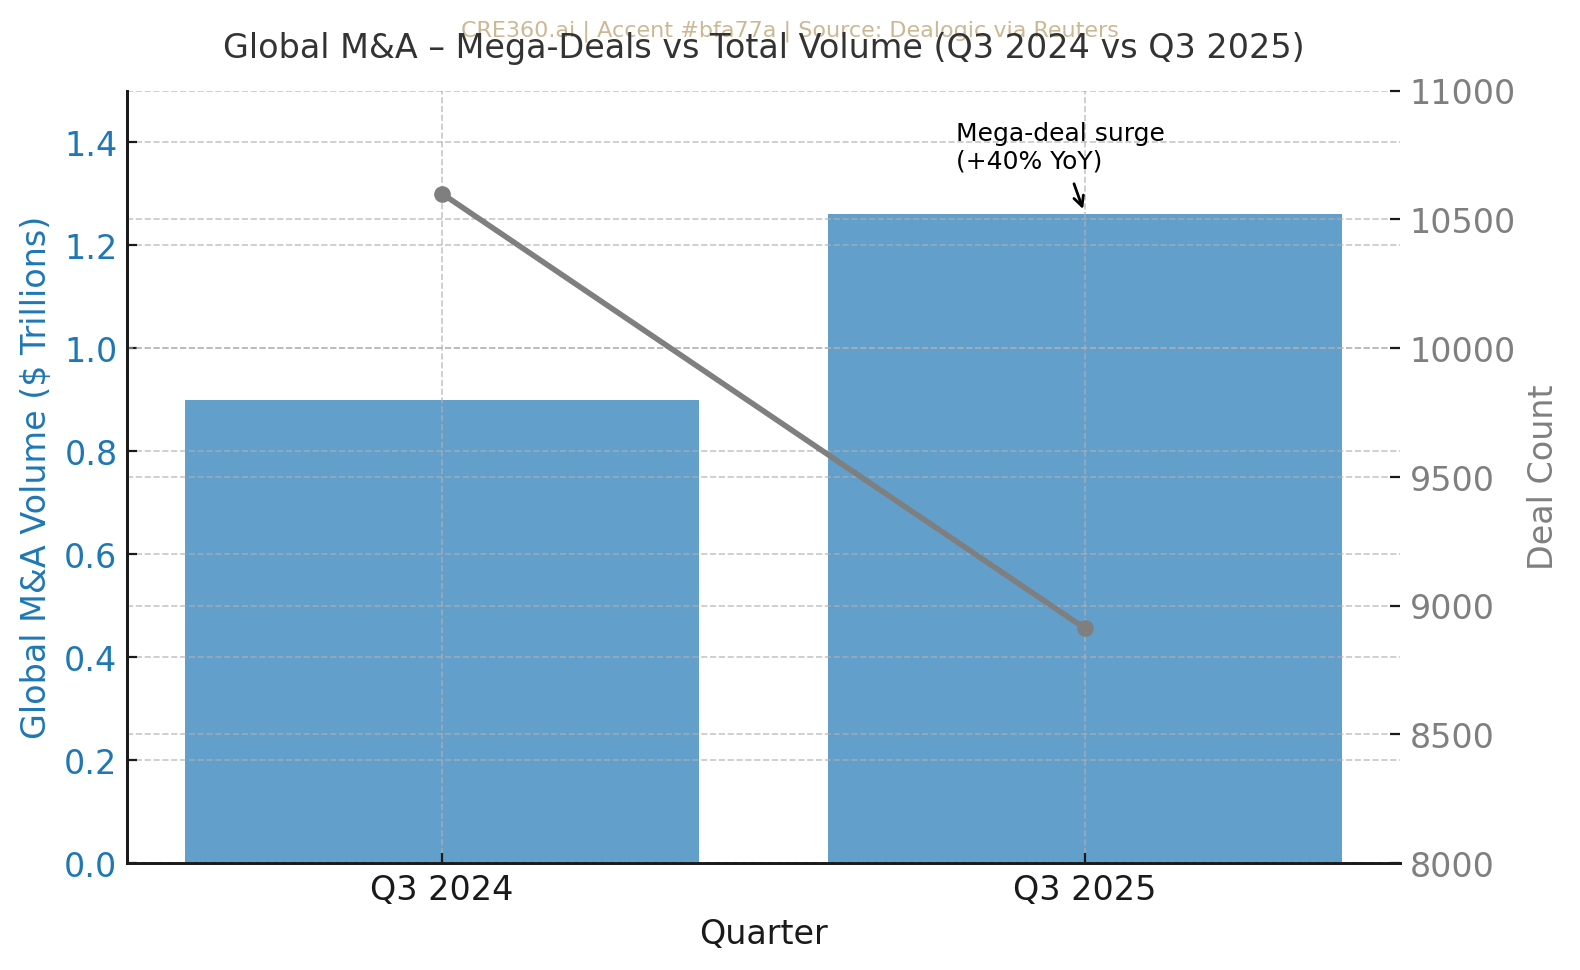
🚨Goldman Sachs faces a wave of senior banker exits amid a slow 2025 deal environment and internal restructuring. Despite losing over a dozen senior dealmakers, the firm remains top-ranked in global M&A advisory, with revenues at their highest since 2021. Global M&A mega-deal volume rose 40% YoY to $1.26 trillion even as total deal count hit a 20-year low. For CRE participants, this signals longer transaction timelines, selective financing, and a continued “flight to quality” across asset and capital markets.

Global M&A volume: $1.26 trillion Q3 2025 (+40% YoY) — [Source: Reuters/Dealogic].
Global M&A deal count: 8,912 (–16% YoY, 20-year low) — [Source: Reuters/Dealogic].
Goldman Sachs YTD stock gain: +38% vs S&P Financials +11% — [Source: Reuters].
Goldman headcount: ~45,900 (–2% QoQ after Q2 cuts) — [Source: Reuters].

Loan Performance. Extended timelines heighten carry and interest-reserve needs; DSCR sensitivity rises as exits delay. Underwrite refinancing cushions at higher spreads.
Demand Dynamics. Buyer pools remain thin; only institutional-grade or strategic assets command pricing power. Middle-market CRE sees slower absorption and longer marketing windows.
Asset Strategies. Bundle or scale disposals to fit “mega-deal” appetite; reprioritize high-conviction projects. Stagger capex to preserve liquidity through drawn-out sale processes.
Capital Markets. Large-cap borrowers still attract balance-sheet lending; mid-tier sponsors face tougher terms and narrower syndication. Expect higher recourse and structure in Q4 term sheets.

Slow deal flow = selective liquidity.
Institutional-grade assets favored; mid-market faces discounting.
Banks trimming exposure; alternative capital key for execution.
Underwrite with conservative spreads and longer marketing horizons.
🛠 Operator’s Lens
Refi. Build rate-lock flexibility; assume 3–6 month closing lag.
Value-Add. Sequence capex with leasing milestones; keep 10–15% contingency.
Development. Stress pro formas for 50 bps higher exit cap; assume slower take-out markets.
Lender POV. Money-center banks prioritize core clients and large tickets; private debt and boutiques fill the gap for $25–100 M financings.

Mega-deals may continue even as volumes remain muted. Q4 bank earnings and Fed policy direction will determine whether M&A—and CRE capital flow—revive into 2026. Watch banker migration to boutiques as a signal of mid-market liquidity potential.

Reuters — “Goldman Sachs Sees Senior Dealmakers Depart as Slow Markets Spur Reshuffle” (Oct 2025). https://www.reuters.com Dealogic — Global M&A Data (Q3 2025). https://www.dealogic.com
Related coverage
Never miss a Signal
Get the daily brief that busy CRE professionals rely on.