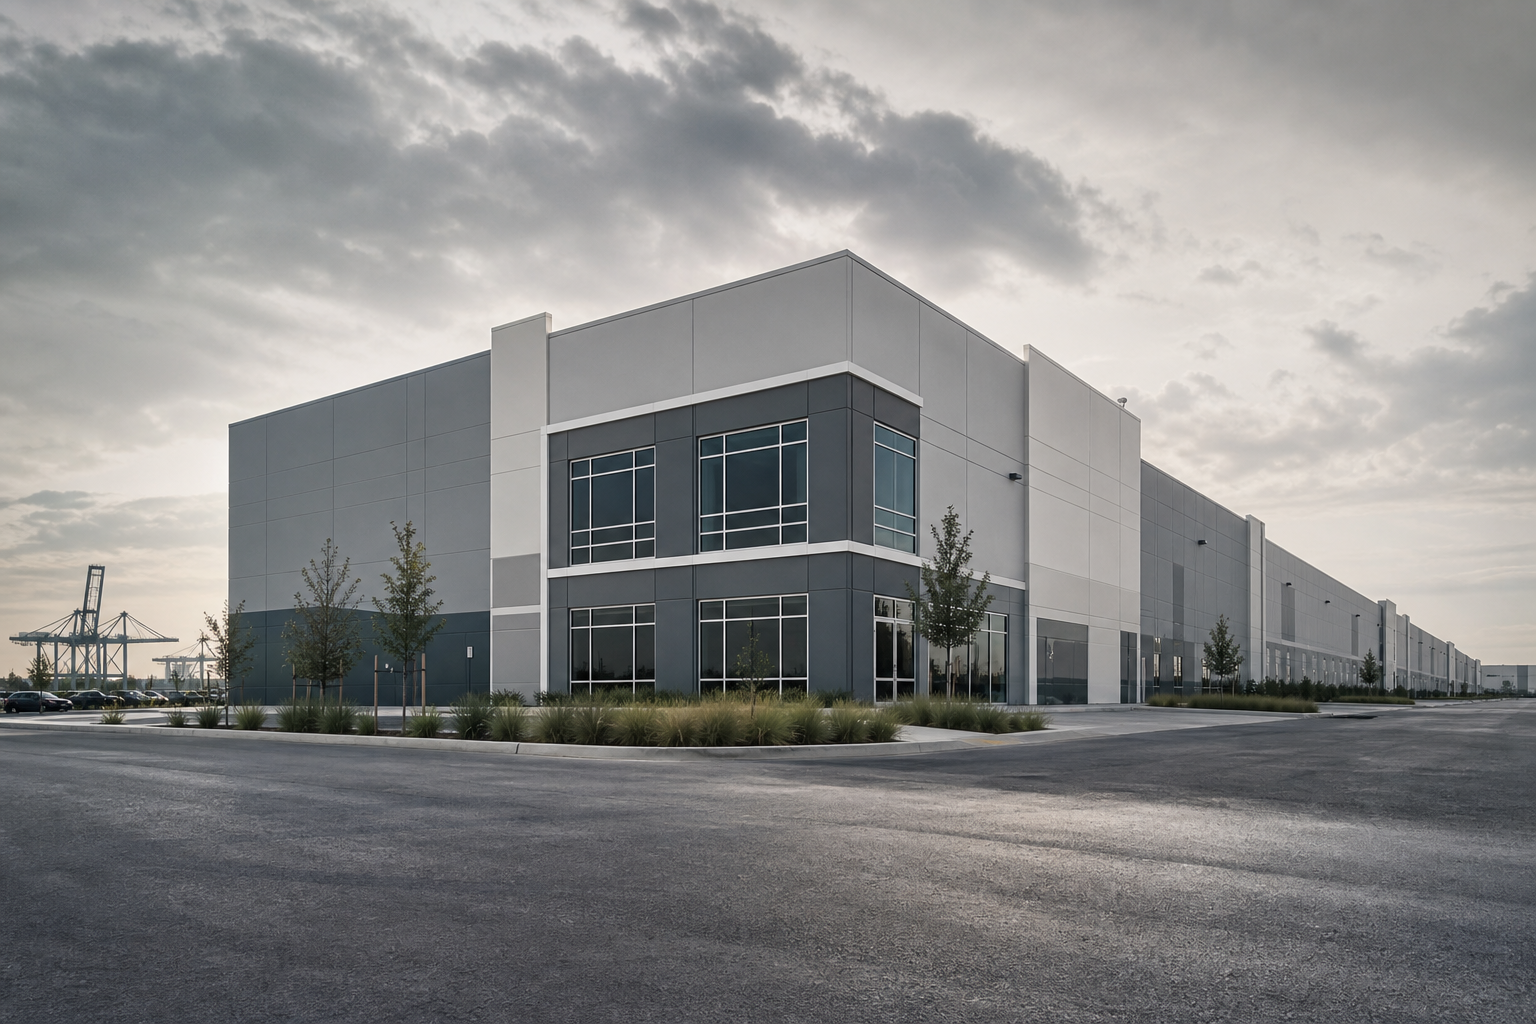
Port-market industrial is usually described as fully absorbed. This building is not.
Canyon Partners Real Estate provided a $67,000,000 senior loan to Kurv Industrial, secured by four buildings totaling more than 278,000 square feet at 575–667 Kapkowski Road in Elizabeth, New Jersey. The buildings delivered in mid-2024. At least 149,202 square feet has leased since — roughly 54% occupancy at closing, a CRE360 calculation rather than a disclosed figure. CBRE's Bill Jurjovec arranged the financing.
That tells you something specific about how infill port land is being valued. Canyon is not underwriting in-place cash flow, because there is not enough of it. It is underwriting the location and the sponsor — and doing so for the second time with Kurv in six months, following a March 2026 Philadelphia refinancing.
The asset sits inside the Port Newark-Elizabeth complex, minutes from Newark Liberty and the New Jersey Turnpike. Rate, term, and loan-to-value were not disclosed.
The tenant detail is a small tell about who is actually taking modern infill space. Osmo, an AI fragrance-design company, is a named in-place tenant — not a third-party logistics provider. Class A infill near a port is increasingly leasing to users who need proximity and power more than they need dock doors.
Sourcing note. The 149,202-square-foot leased figure appears only in Real Estate NJ, not in the issuer release. It is the most load-bearing number here and the least corroborated. All other coverage traces to a single press release.
Implications. Lenders are pricing infill port land on replacement-cost logic rather than on current occupancy. That is a defensible position when there is no more land, and a dangerous one if lease-up stalls past the loan term — and without a disclosed term, that risk is unmeasurable from the outside.
For sponsors, the read is more encouraging: a partially leased spec building in a supply-constrained submarket is still financeable at scale. That was not obviously true twelve months ago.
Related coverage
Key Takeaways
- In a port market with no land left, lenders are underwriting the dirt rather than the rent roll
- A partially leased spec building in a supply-constrained submarket is still financeable at scale
- Without a disclosed loan term, the lease-up risk is unmeasurable from outside
PR Newswire, September 9, 2026 · Real Estate NJ, September 10, 2026 · ROI-NJ, September 9, 2026 · Institutional Real Estate Inc., September 2026
Never miss a Signal
Get the daily brief that busy CRE professionals rely on.