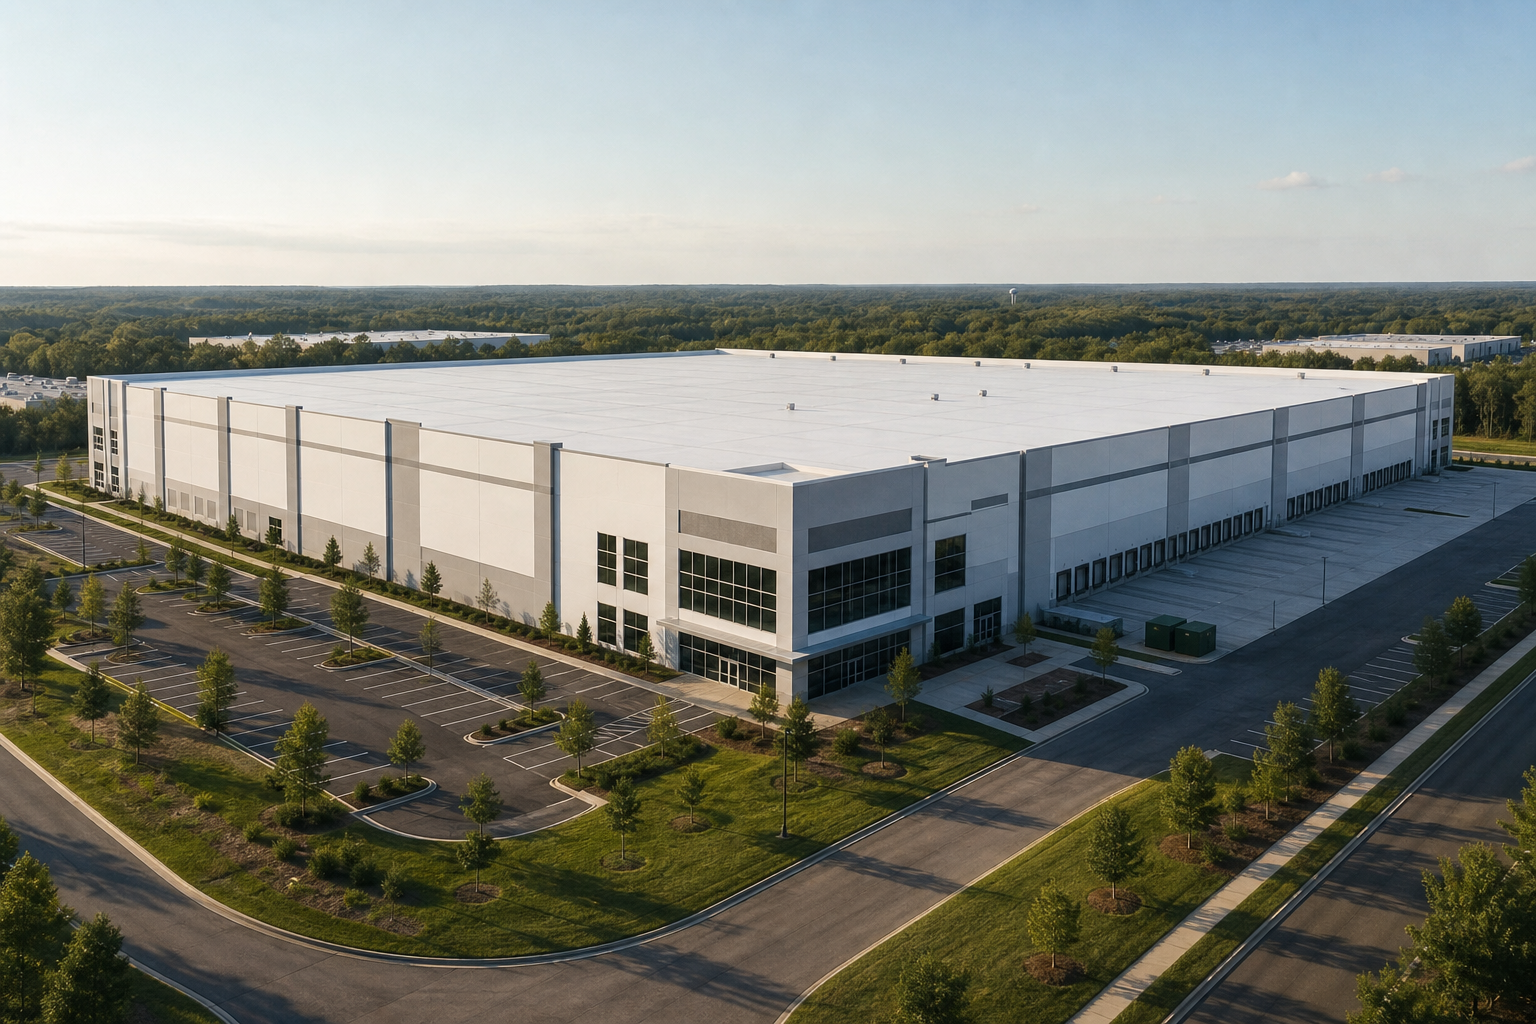
Data-Center Demand Just Leased 935,000 Square Feet of Warehouse
J.E. Richards takes an entire Stafford, VA building — the largest industrial lease ever between D.C. and Richmond.
CRE360 Editorial Desk·Sep 16, 2026
Topic archive
Logistics, warehouse & last-mile
105 published items
The Grid Just Got A Number
One tenant published a power requirement large enough to reprice construction.
Industrial's Free Money Ran Out
The premium on new leases halved in a year. That was the engine.
The Capital Market Did Not Freeze. It Sorted.
A $1.63B apartment trade, a 74%-levered warehouse deal, and a record office delinquency all printed in 48 hours. That is the sort.
Private Capital Buys the Public Discount
Brookfield and CPP's $5.2B move on LXP says the industrial reset is over — and public REITs look cheap.
The Recovery Nobody Built For
Office, industrial, and retail are all recovering into the emptiest pipelines in a decade — and paying up to finance it.
The Warehouse Becomes Infrastructure
Prologis raised guidance twice this year — because industrial demand stopped being about e-commerce.
The Trade Deal That Didn't Renew
Washington let USMCA lapse into annual review — and put a policy asterisk on nearshoring.
The Pro Forma Is Already Wrong
Construction input costs are rising at the fastest pace since 2022 — and tariffs are the engine
The Map for Data Centers Just Got Smaller.
Three city councils and a congresswoman moved against new builds in five days.
The Repricing Is Here and Rent Growth Must Carry the Load
What the Data Is Really Telling Developers
Industrial Rent Growth Turns Negative as Supply Catches Up
Industrial rent growth turns negative as rising supply and weaker tenant demand reshape warehouse pricing across all size segments.
Industrial 2025 Recap & 2026 Outlook
Overview of industrial performance in 2025 and what to expect in 2026
🟡CRE Financing Stalled as Rate Relief Stays Elusive
Higher-for-longer Fed stance keeps deals on ice, with borrowers and lenders waiting for clarity.
🟡Self-Storage Market Stabilizes in 2025
Pandemic boom cools into a steady, resilient asset class.
Fed Rate Cut Signals CRE Lending Revival: Q2 Originations Surge 66%
Fed Governor signals September rate cut, boosting commercial real estate lending with 92% odds of 25 bp reduction, potentially easing financing costs and market recovery.
J.E. Richards takes an entire Stafford, VA building — the largest industrial lease ever between D.C. and Richmond.
A single tenant just told the market it will more than triple its footprint by 2032.
August producer prices split the metals complex apart for the first time this cycle.
Kearney, Nebraska legalized data centers and permitted one nearly four times the size of the bitcoin mine it replaces — in a single night.
A debt fund refinanced Class A port-market industrial that is roughly fifty-four percent leased two years after delivery.
Ares bought a Target distribution center and a LaserShip hub in Miami-Dade on the same ticket.
Link Logistics exits Benicia at $163.69 a foot on rents the buyer calls below market.
A five-year, full-term interest-only loan on 243,496 square feet — and no purchase price anywhere.
Texas classified Galaxy's data center load — and most of it came back conditional.
A $1.2 billion cross-border close where only a quarter of the consideration was money.
294,700 speculative square feet break ground in Oregon's Silicon Forest.
Bedford's advanced manufacturing campus is two years old and one-third leased. It got $62.5M anyway.
Same site, same sponsor class, 16.7% less program than the zoning allows.
Core institutional capital returned to industrial — but only for signed credit.
Fund V exited 46 buildings eleven weeks after Fund VI bought into the same corridor.
Move-outs beat deliveries by 15 million cubic feet — and almost all of it was old.
ExchangeRight steps outside necessity retail for a single-tenant industrial asset at $126 a foot.
WareSpace opens its second Denver site at unit sizes institutions never underwrite.
Green Point starts speculative construction 30 miles north of Austin.
EQT buys 22 Southern California industrial properties from a seller shedding above-market leases.
Twenty Midwest logistics assets, one full-cycle exit, six markets nobody called core.
Ares and a Stonemont and PCCP venture paid up for infill warehouses far from the coasts.
216,000 square feet fully spoken for in the industrial subtype nobody builds on spec.
Big-box occupiers are committing to more space for longer, and the Inland Empire is leading.
Institutional capital is bidding essential-goods logistics near the port, not speculative e-commerce big-box.
Speed Bay first Northeast deal is a bet on infill last-mile, not big-box logistics.
Industrial debt is not just available, it is aggressive, when the boxes are already full.
Million-square-foot industrial leases more than doubled in H1, occupiers are committing again.
A global asset manager just took down eleven infill industrial buildings across Chicago and Minneapolis in a single move.
Brookfield and CPP will buy LXP Industrial for $5.2B, all cash, no financing condition.
Prologis posted record leasing, raised guidance twice, and grew its power pipeline to 5.8 gigawatts.
Equus buys a fully leased, 2023-vintage infill park with life-sciences and advanced-manufacturing tenants.
Lincoln buys value-add Class A industrial to lease into South Sound manufacturing.
EastGroup raised acquisition guidance and re-leased space 35% above prior rents — the opposite of a rollover.
A single-asset warehouse print marks the I-4 corridors clearing price.
Boomerang bets on scarce delivered cold storage while tariff risk stalls the field.
Majestic Realty and Salt River Pima-Maricopa sign a landmark lease for a ~1M-SF park.
Bridge Logistics pays $222.86/SF for a Harbor Freight distribution center near Tacoma.
Velo3D leases a 288,700-SF Bay Area facility to move metal 3D printing from prototype to production.
A 1.47M-SF, two-building trade puts a fresh pricing print on the most-watched industrial market.
Big-box tenants came back at scale — and modest new supply is doing the rest.
AllianceTexas keeps building at scale while most of the market waits for the pipeline to clear.
The largest logistics landlord just told the market industrial demand is broadening, not fading.

A 571,000-SF Chicago purchase signals occupiers taking permanent positions in scarce infill space.
A first portfolio buy signals institutional capital is now chasing the most fragmented corner of industrial.

The largest occupiers are back to leasing million-foot warehouses in the Sun Belt.
Occupiers signed 250 million SF in Q1 and keep going bigger, even with vacancy near 7%.
A $42M SoCal lease and a 1.2M-sf Texas groundbreaking show occupiers committing long again.
2.7M SF of leases push occupancy to ~98% — including a 53-year ground lease in Hawaii.
Prologis posts record Q1 leasing and raises guidance as AI demand spills into industrial.
Fully leased, sub-4% vacancy, embedded rent upside — the infill core bid is back.
Leasing is on track for an all-time high even as net absorption stays below trend — the market is sorting.
Spec industrial and master-planned land are still pricing growth where power, freeways, and acreage align.
3PLs and manufacturers are reabsorbing the largest warehouses — and AI is a driver.
A 767K SF Houston box, leased to 2028, anchors BLP's largest Texas buy since 2021.
Industrial net-lease rose 15% to $7.1B in Q1; retail net-lease fell 21% to $2.7B.
Hut 8's Beacon Point campus signs a 15-year, 352 MW lease worth $9.8B — triple-net, take-or-pay.
Makarora and Ares paid a ~50% premium to take Plymouth Industrial private — quantifying the public-vs-private gap.
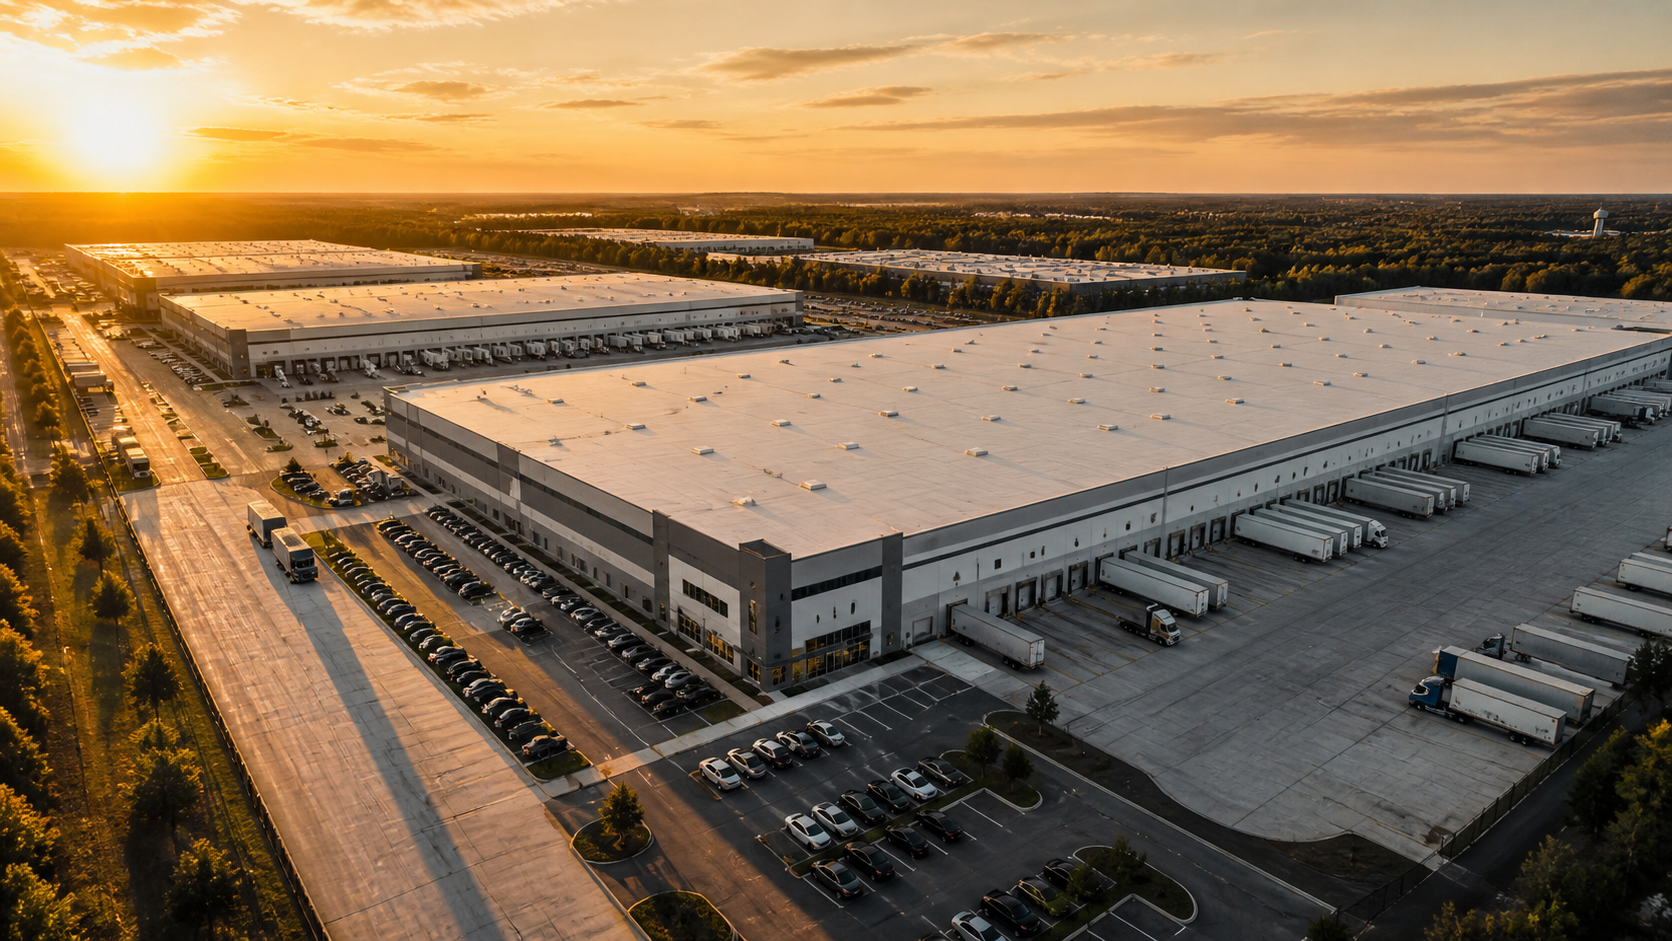
ILPT priced $1.62B in fixed-rate logistics CMBS at 5.71%, setting the public comp for Class A industrial debt.
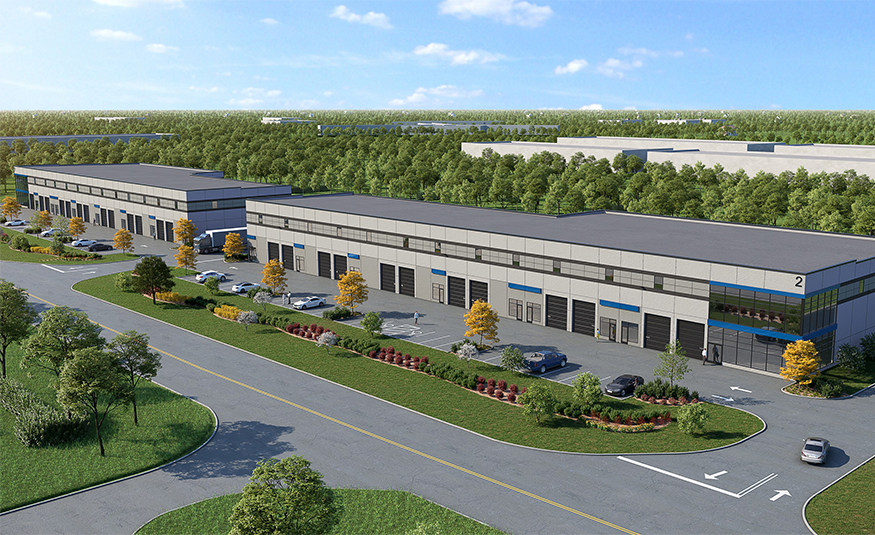
Brennan Investment Group expands its Midwest footprint with a multi-market acquisition, reinforcing investor confidence in infill industrial fundamentals.
FHFA-sets-2026-multifamily-caps-88b-each
El Paso capacity jump reflects a tenant-driven pivot toward border-oriented warehousing and LTL integration
Strategic consolidation and operational focus shape evolving frameworks for scale in logistics asset management.
October’s 21% jump in U.S. industrial construction starts reveals a two-speed market as megaprojects drive headline growth, outpacing smaller developments.
EQT’s $4.2B exit and rising vacancies mark a maturing U.S. industrial cycle as supply soars, regional splits widen, and capital recalibrates risk and pricing.
E-commerce expansion steadies Midwest warehouse demand as construction revives.
Leasing surge resets pricing power in tight nodes
Balanced fundamentals signal a durable floor in logistics property performance.
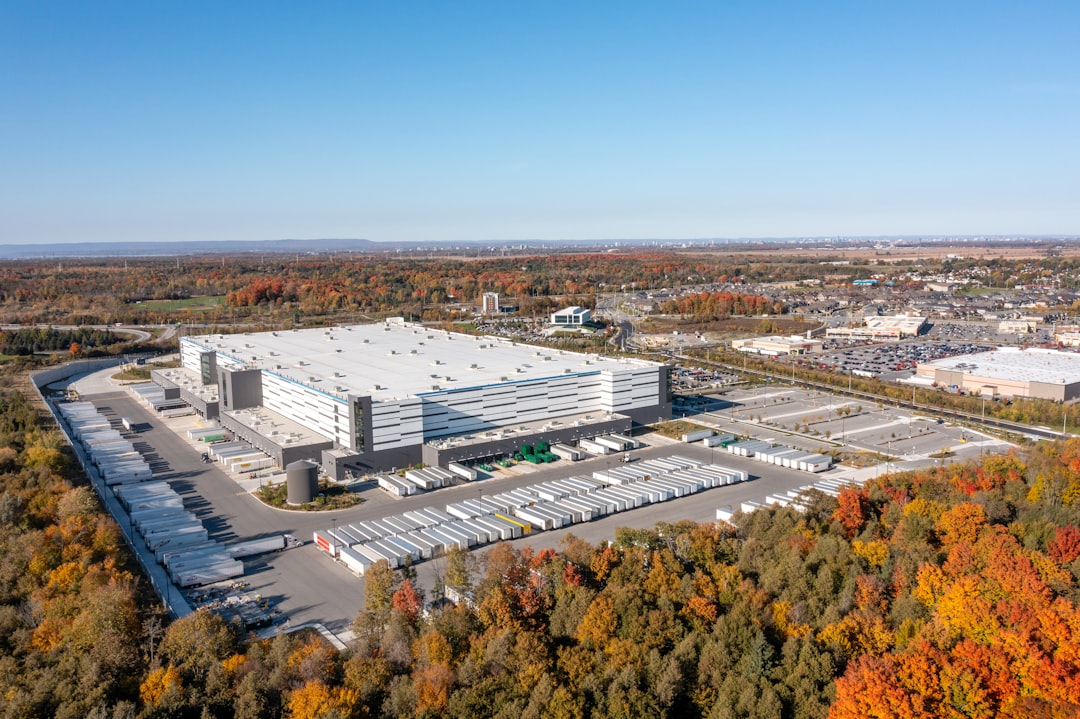
Premium-priced take-private underscores private equity’s conviction that warehouse cash flows outlast public-market fatigue.
Domestic production and data-center demand keep the industrial engine running hot.
Large-check capital goes granular as portfolios freeze and sector rotation reshapes U.S. CRE allocation.
Large-Cap Buyers Reprice and Re-Enter NYC Office
GIC and ADIA’s $1.1 billion refinance of Deutsche Bank Center restores confidence in trophy-grade CMBS execution.
Asset swap signals shift toward equity partnerships and M&A-driven growth under sustained rate pressure.
Lenders maintain strong appetite for large, stabilized warehouse portfolios amid a moderating but resilient industrial market.
Institutional landlords now control 17% of U.S. logistics assets, reshaping valuation, yield, and competition.
Dallas landlord redeploys into industrial, betting on tight shallow-bay supply and sustained rent growth.
New York Life’s $130M refinancing confirms stabilized infill industrial remains highly financeable in Southern California.
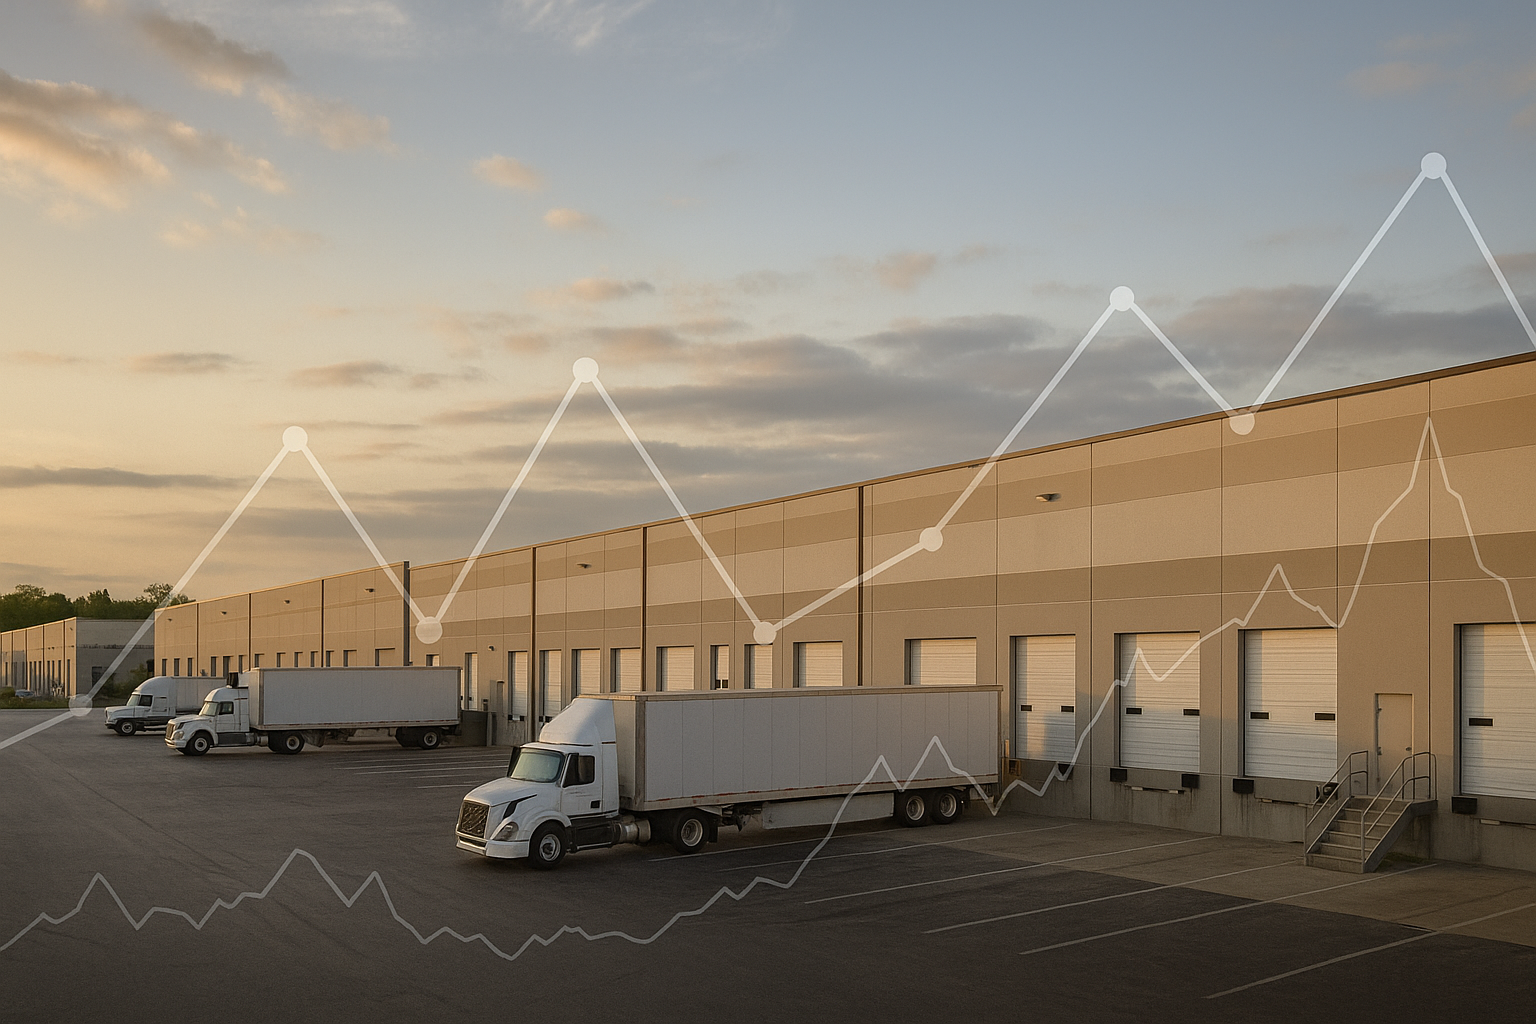
Stabilized, small-bay portfolio clears at ~$136/SF—mid-6% yield signals durable demand for Beltway last-mile space.
Fortress buys four UPS assets; pricing and credit signal resilient industrial financing.
Corporate balance sheets, not debt markets, are fueling the Midwest’s emergence as a hyperscale AI infrastructure hub.
Rising vacancies press leasing and pricing strategies in U.S. industrial markets.
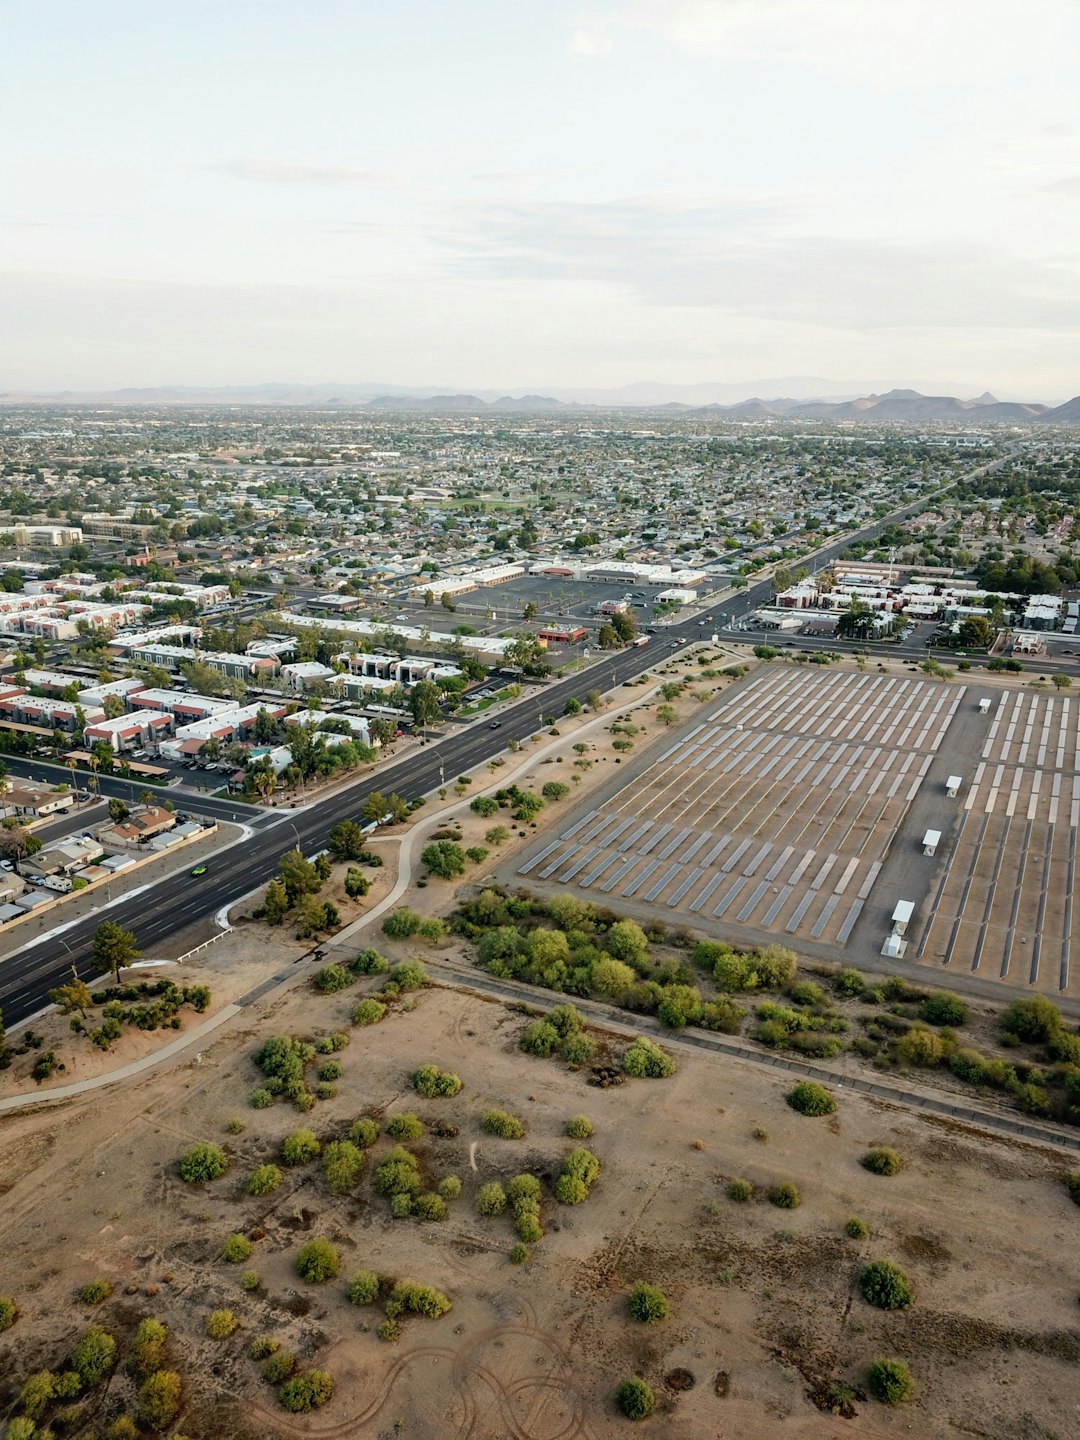
U.S. Industrial Market Shows Resilience Amid Evolving Tenant Strategies
High-leverage financing underscores market confidence in Phoenix's industrial assets.
Multifamily and data centers thrive amid rising office delinquencies; tailored strategies are crucial.
Foreign Capital Backs New Joliet Logistics Build. Mapletree’s 418,880-SF plan lands in a thinning 2026 pipeline, supportive for rents and debt execution.
Industrial financing resilience: Starwood’s $930M refinancing shows lenders’ deep appetite for logistics portfolios, even at higher rates, with below-market rents providing embedded growth.
Tri-State industrial market shows resilience with 8.7% vacancy, stable rents, and robust 3PL demand amid rising port throughput and strategic lending landscape.
Selective lending continues for top-tier multifamily and industrial assets as bank hapoalim and starwood provide $720M in strategic NYC refinancing amid challenging CRE market.
Southern California industrial market shows resilience: MetLife's $165.5M portfolio sale signals strong investor confidence amid rising vacancies and record-high warehouse rents.
Trusted Daily
40,000+
Daily Subscribers
Brokers, investors, developers, and lenders open CRE 360 Signal™ every morning for the market intelligence that moves their decisions.
Free. Independent. Editorially rigorous.
Follow the Signal
Add your profile URLs from the Editorial Desk → Social links.